Scroll Up Top
Download icon
Download

August was defined by divergence within developed-market yield curves rather than a broad directional move in rates. Short-dated yields rose as investors reassessed the likelihood that the policy cycle could shift back toward tightening, while long-dated yields were stable or lower, leaving curves flatter across most major markets. Spread sectors were firm but increasingly dispersed: high yield and emerging market debt tightened materially, while investment grade was largely unchanged. Volatility also declined across both rates and equities.

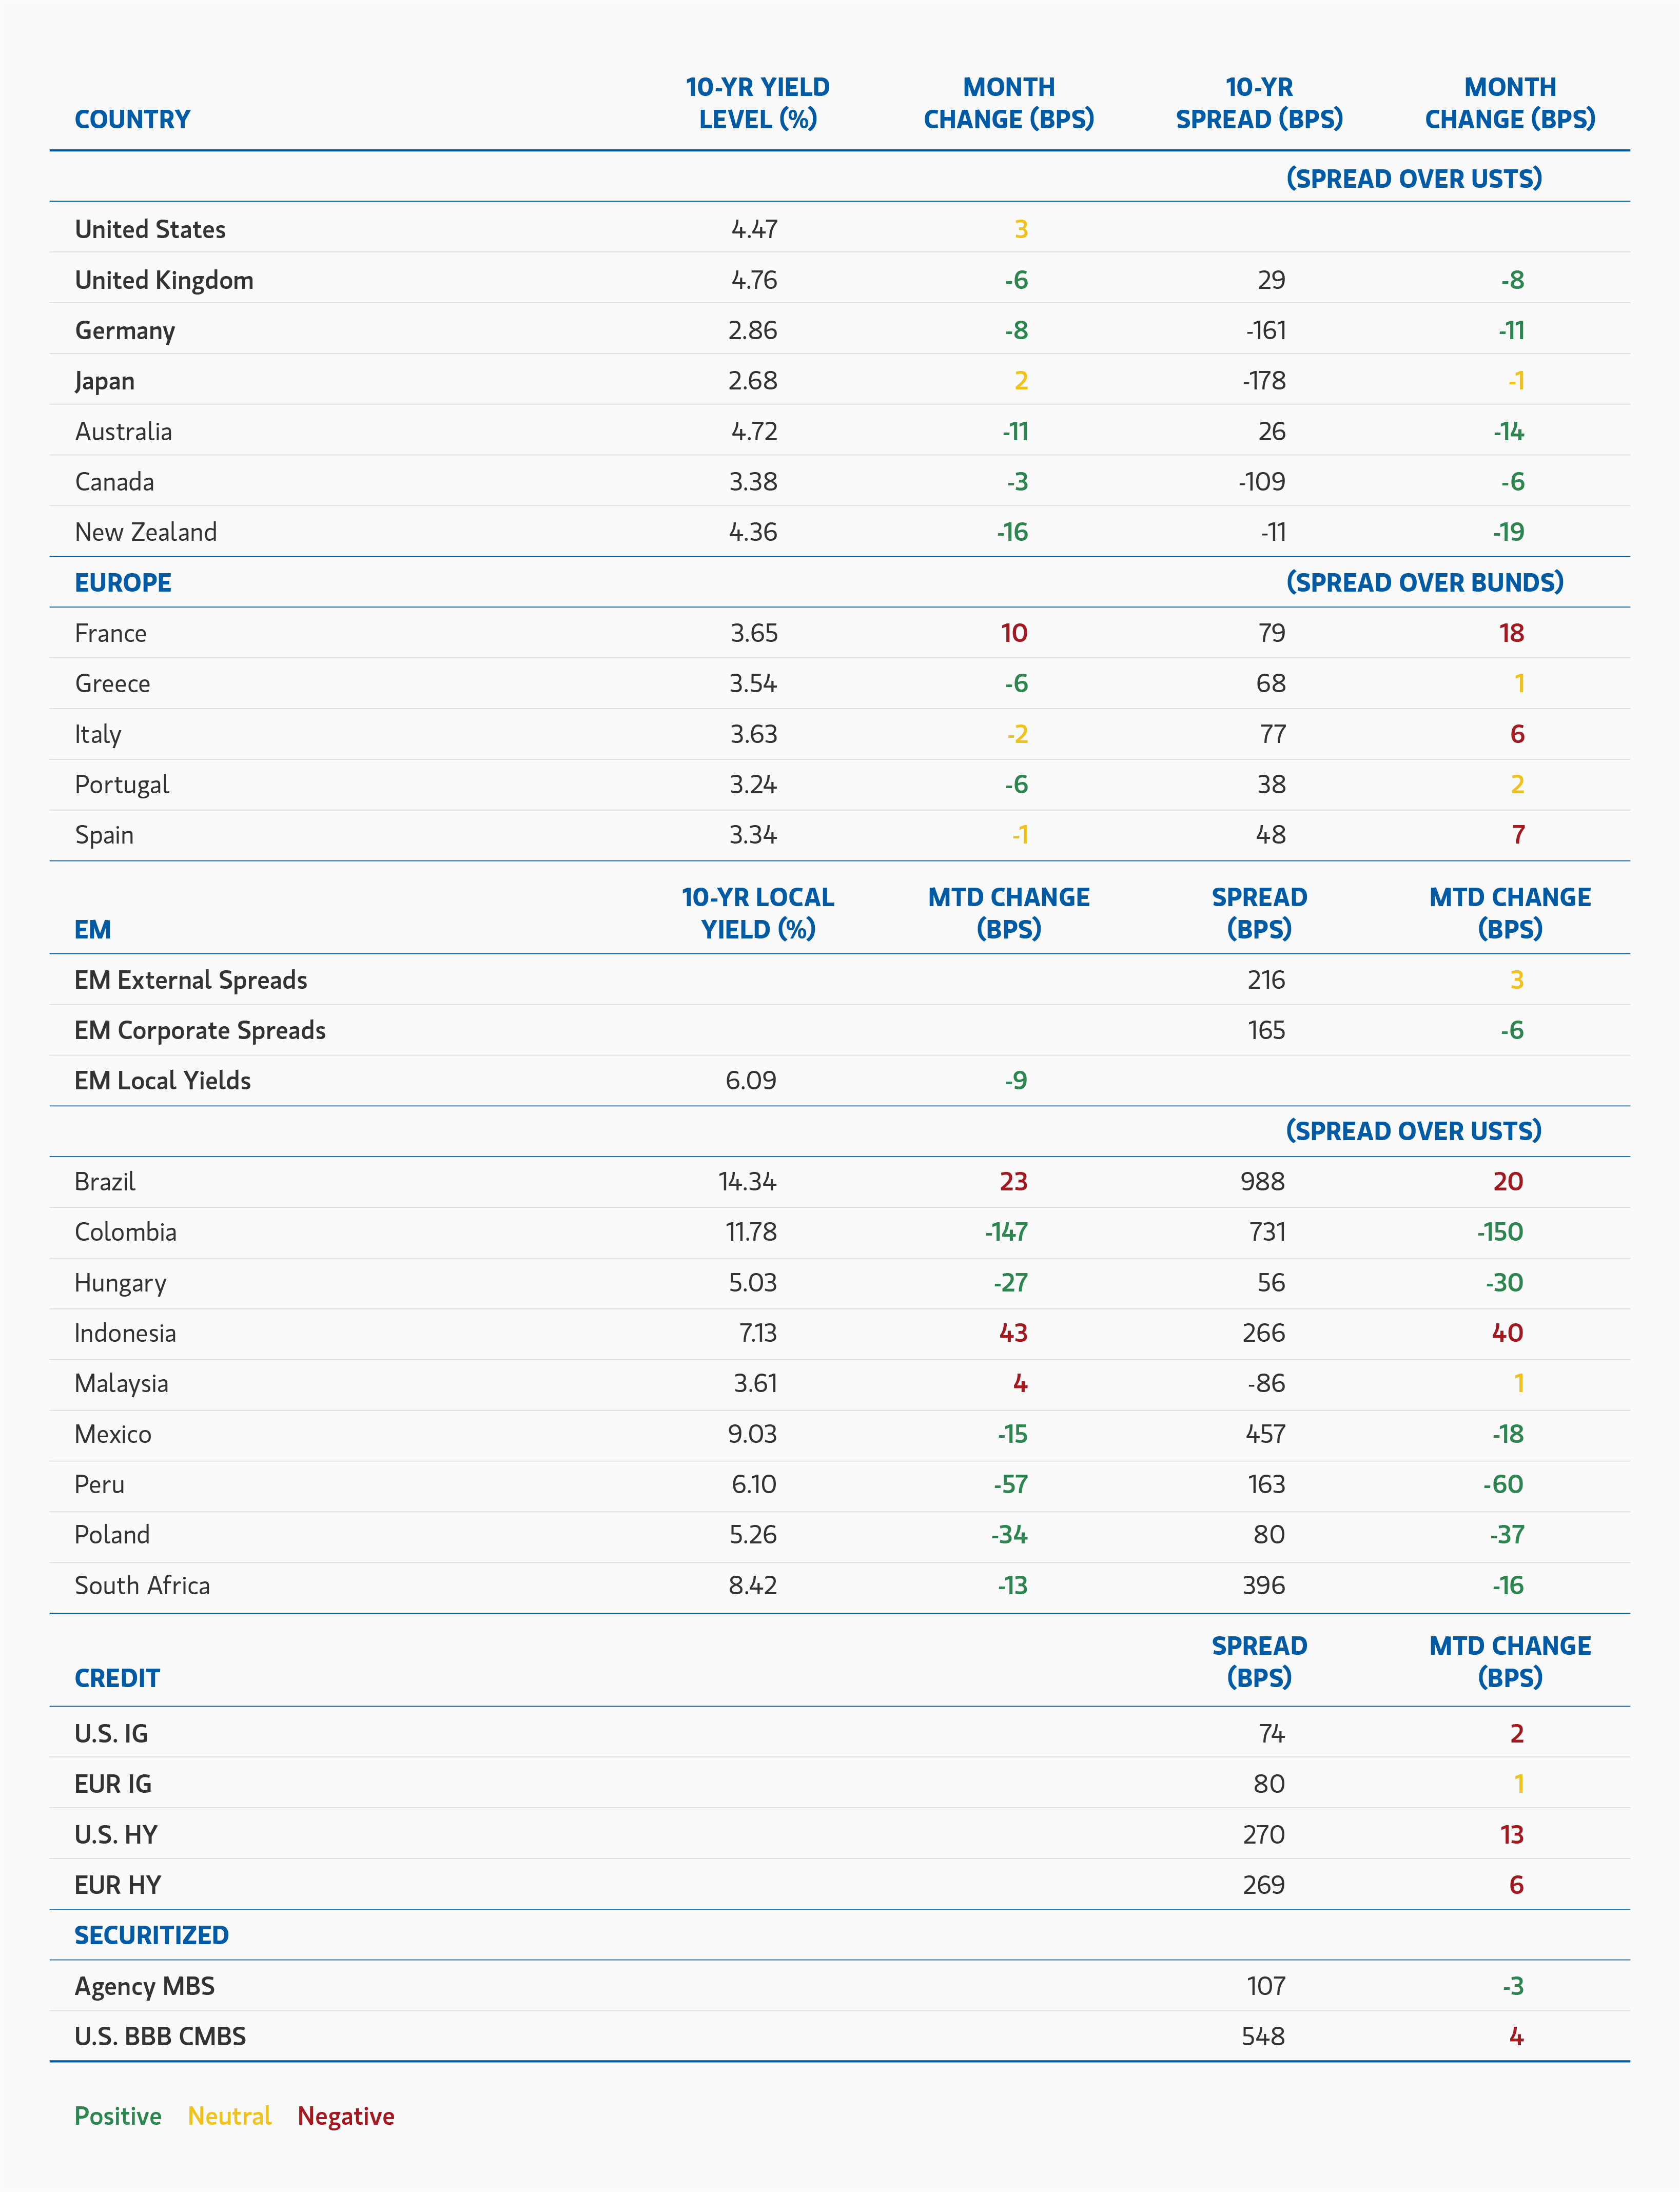
The rates move was relatively contained in the U.S. The 10-year Treasury yield rose 1.5 basis points (bps) to 4.75%, while the 2-year yield increased 5bps and the 30-year declined 3bps, flattening both the 2s10s and 5s30s curves. Ten-year breakevens widened 4bps as real yields declined, suggesting that the modest increase in nominal yields was driven more by inflation compensation than by tighter real rates. Elsewhere, moves were more pronounced and largely country-specific. Ten-year yields rose 17bps in Australia, 15bps in Japan, and 12bps in Germany, while UK gilt yields were broadly unchanged. Japanese yields reached their highest levels since the mid-1990s, reflecting expectations for further Bank of Japan tightening alongside concerns around fiscal expansion.

Federal Reserve communication was the central policy event of the month. Following the late-July decision to leave rates unchanged at 3.50%-3.75%, despite three votes for a 25bps hike, markets entered August with a September increase close to fully priced. Expectations eased following a softer July Consumer Price Index (CPI) report, then rose again after Chair Warsh's Jackson Hole address reaffirmed the Fed's 2% personal consumption expenditures (PCE) inflation target, characterized financial conditions as insufficiently restrictive, and emphasized the need for further progress on underlying inflation. With PCE inflation at 3.7%, the message was viewed as notably firmer than in July. September hike expectations moved back above one-half, while the long end remained relatively stable. Neither the European Central Bank nor the Bank of England met during the month.

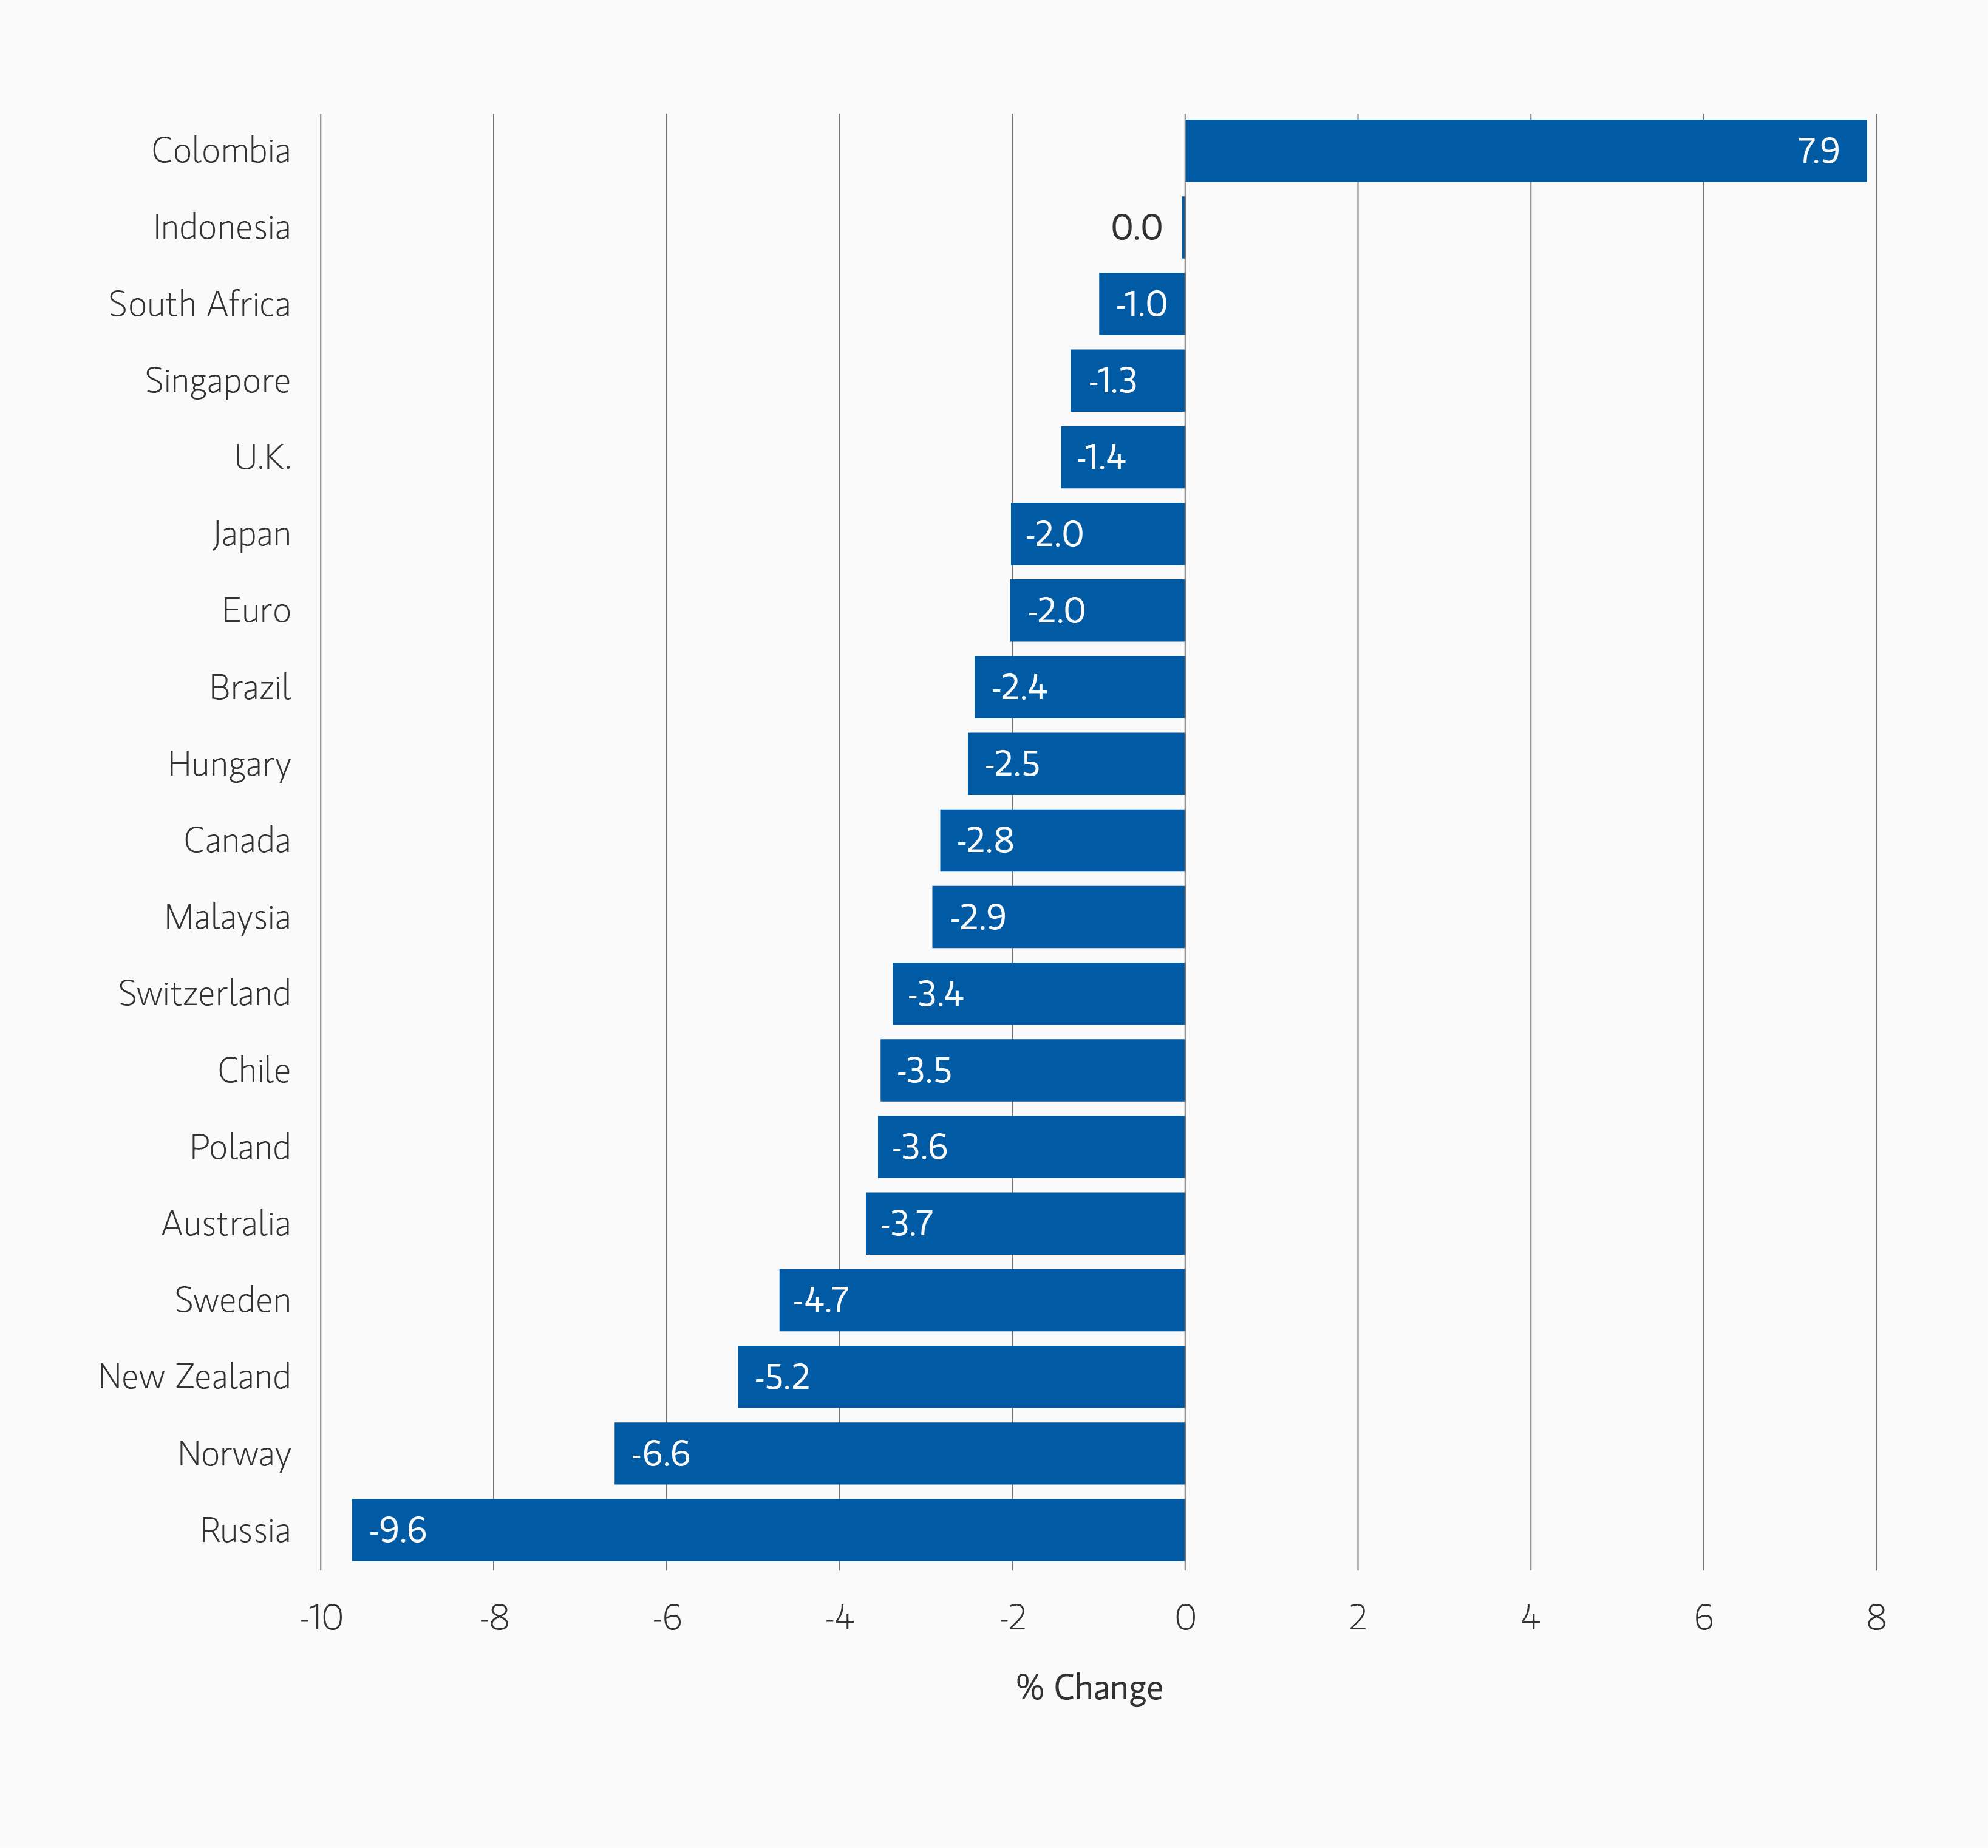
Foreign exchange markets extended July's reversal of U.S. dollar strength, with the broad dollar index declining 0.9%. Commodity and higher-beta currencies generally outperformed, with the Korean won, South African rand, Australian dollar, and Mexican peso all appreciating. The yen was the weakest major currency, depreciating 1.5% despite higher Japanese yields. Emerging-market currency performance remained highly differentiated, with the Brazilian real and Colombian peso weakening against a broadly softer dollar.

Credit markets were notably stable at the top of the capital structure. U.S. investment grade spreads finished unchanged at 78bps option-adjusted spread (OAS), while Euro investment grade remained at 79bps. Shorter maturities modestly outperformed longer-duration credit in both markets, while sector dispersion largely offset at the index level. Sterling credit was the exception, tightening 3bps to 86bps. The limited spread movement reflected a balance between robust corporate fundamentals and strong technical demand on one side, and continued supply from M&A activity and AI-related capital expenditure on the other. Strong Q2 earnings helped reinforce the underlying fundamental backdrop, but with spreads already close to cycle tights, carry and roll rather than further compression remained the dominant sources of return.

High yield delivered the strongest spread performance of the month, though dispersion remained pronounced. U.S. high yield tightened 18bps to 261bps and Euro high yield tightened 12bps to 260bps. The move was concentrated in higher-quality cohorts, with BB and single-B credits leading, while CCC-rated debt widened 32bps in the U.S. and by a similar amount in Europe. The divergence suggested continued demand for carry in stronger credits rather than a broad-based improvement in lower-quality fundamentals. AI and data-center financing also remained an important feature of primary issuance, reinforcing the need for selectivity within newer and more capital-intensive areas of the market.

Leveraged loans generated solid returns during August, supported by carry, modest price appreciation, and continued collateralized loan obligation (CLO) demand. The asset class returned approximately 93bps during the month, with roughly one-third of the return coming from price appreciation. Performance remained highly differentiated, however, with software continuing to lag the broader market amid persistent concerns around AI-related disruption. Outside software, loan prices were comparatively stable, while robust CLO creation continued to provide an important source of technical demand.

Securitized markets benefited from lower rate volatility and increasingly supportive mortgage technicals. Agency mortgage-backed securities (MBS) spreads tightened 4bps to approximately 112bps versus comparable Treasuries as implied rate volatility declined. Elevated mortgage rates also reduced refinancing activity, while slower seasonal issuance helped constrain new agency supply. Mortgage rates remained elevated during the month but eased to 6.66% by month-end. Securitized credit moved only modestly, with BBB commercial mortgage-backed securities (CMBS) tightening slightly and AAA asset-backed securities (ABS) finishing somewhat wider. The combination of lower volatility and tighter supply provided support without requiring a material improvement in underlying credit fundamentals.

Emerging markets (EM) outperformed, reversing July's widening. External sovereign spreads tightened 10bps to 217bps and EM corporate spreads tightened 11bps to 199bps, with gains broad across regions and ratings. The Middle East, which had underperformed in July, tightened 13bps as regional risk premia compressed. Local markets remained highly differentiated, with yields falling materially in Indonesia and Brazil while rising in Poland and Mexico. Policy easing also continued selectively, including 25bps cuts in both Brazil and Hungary. The rally left credit valuations at very tight levels across several parts of the asset class, reinforcing the importance of local rates, currencies, and country-specific opportunities rather than broad spread exposure.

Overall, August reversed several of July's dominant market moves: curves flattened after steepening, Federal Reserve communication was interpreted as more hawkish, spread sectors recovered, and volatility declined. What remained consistent was the persistence of dispersion across ratings, regions, and sectors. With spreads still near historically tight levels and the policy outlook increasingly skewed toward renewed tightening, carry, relative value, and active security selection remained the primary drivers of excess return.

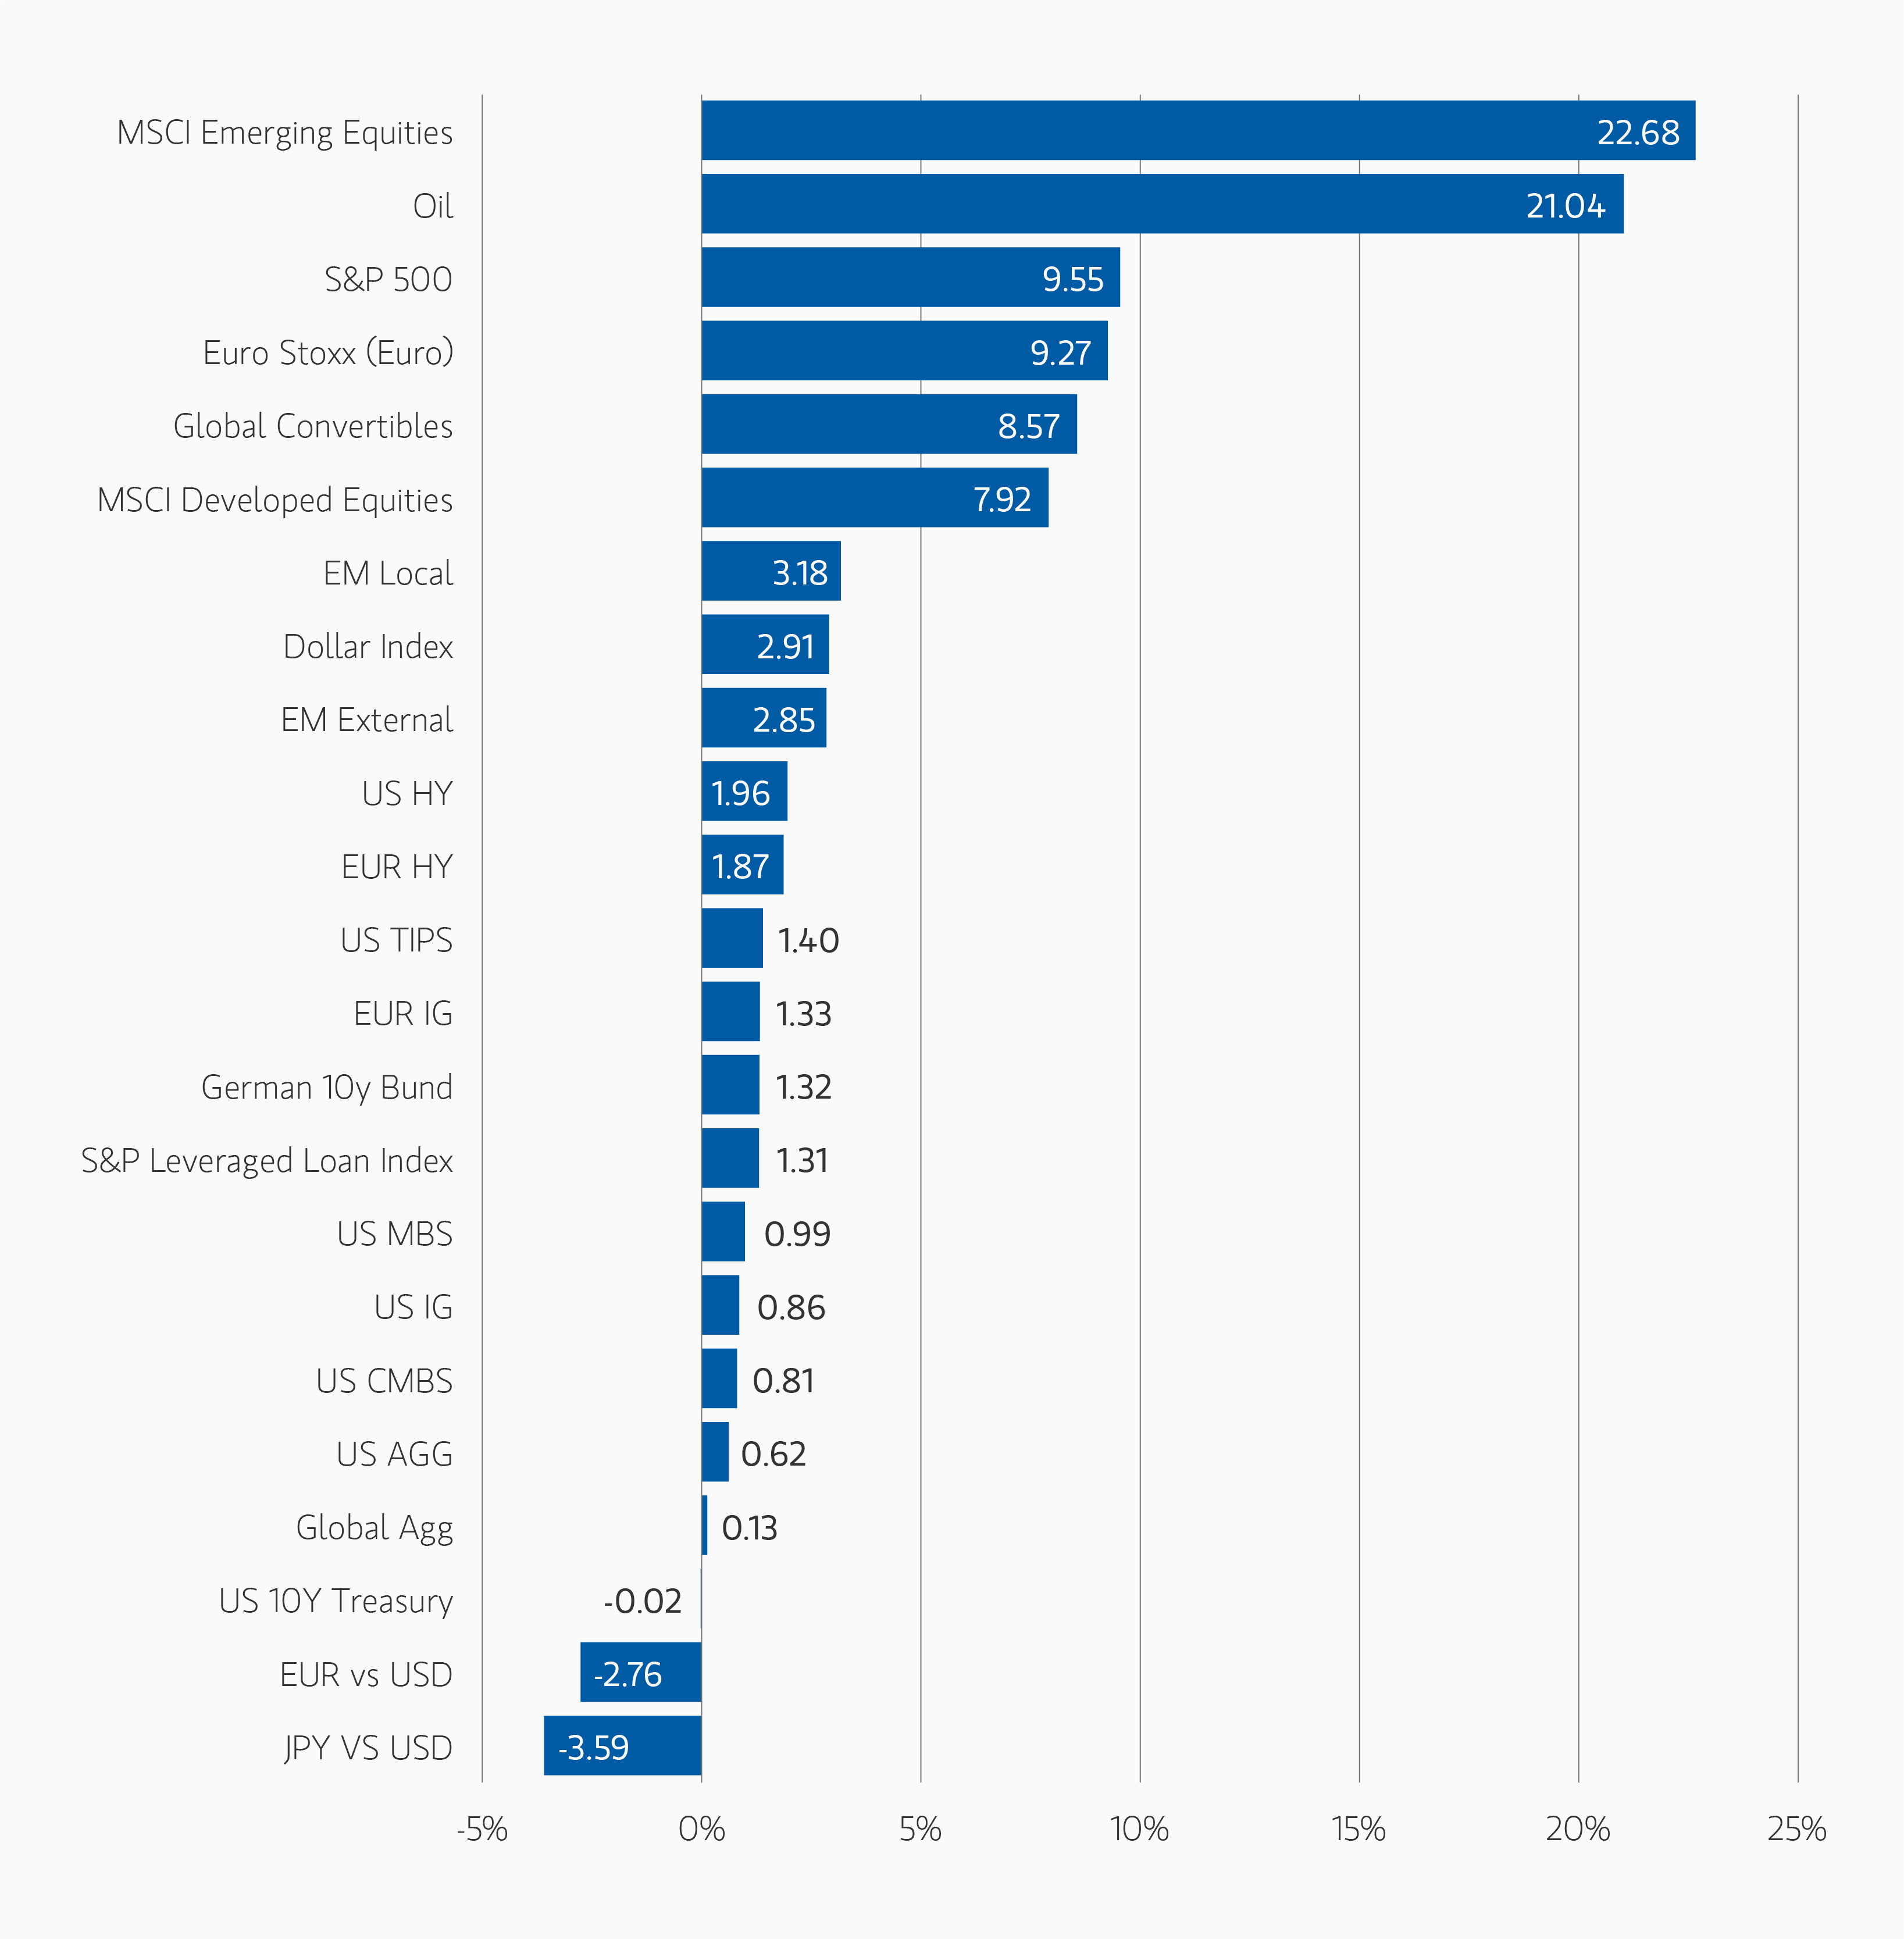
Display 1: Asset Performance Year-to-Date
insight_built-on-resilience_display1.png

Note: USD-based performance. Source: Bloomberg. Data as of August 31, 2026. The indexes are provided for illustrative purposes only and are not meant to depict the performance of a specific investment. Past performance is no guarantee of future results. 

Display 2: Currency Monthly Changes versus USD
insight_built-on-resilience_display2.png

Note: Positive change means appreciation of the currency against the USD. Source: Bloomberg. Data as of August 31, 2026.

Display 3: Major Monthly Changes in 10-Year Yields and Spreads
insight_built-on-resilience_display3.png

Source: Bloomberg, JPMorgan. Data as of August 31, 2026.

Broad Markets Fixed Income Global Asset Allocation and Outlook

Developed Market Rate/Foreign Currency
(Long duration, neutral curve positioning, selective high-carry FX)
Our views are grounded in a macro environment where country differentiation is becoming increasingly important. In the U.S., resilient labor-market data, firm consumption, and persistent inflation pressures have led investors to reprice monetary-policy expectations toward a more restrictive path than was anticipated at the beginning of the year. Elsewhere in developed markets, much of this adjustment occurred earlier, though inflation, energy prices, fiscal dynamics, and differing growth trajectories continue to shape central-bank expectations.

Against this backdrop, we maintain a long-duration stance across developed markets, expressed selectively in regions where growth appears more vulnerable to tighter financial conditions and valuations are compelling. Exposure remains focused on short-maturity rates in Canada and New Zealand, alongside selective euro-area duration, including France. This positioning reflects the greater scope for economic weakness outside the U.S. and the potential for regional policy paths to diverge.

Inflation remains a central macro risk. Although market-implied inflation expectations have fluctuated, underlying price pressures and uncertainty around the Federal Reserve’s reaction function continue to support exposure through U.S. breakevens across intermediate and longer maturities. We continue to see value in hedging portfolios against the risk that inflation remains above target for longer than markets currently anticipate.

We remain broadly neutral on directional curve exposure, while retaining selective relative-value positions where differences in policy, growth, and valuation create more attractive opportunities. These include cross-market positions within Europe and targeted curve exposure in Australia, rather than a broad global steepening or flattening view.

In foreign exchange, we continue to favor selective high-carry emerging-market currencies where fundamentals and valuations remain supportive. Our positive view is focused on the Mexican peso, funded against lower-yielding European currencies including the euro, Swiss franc, and Swedish krona. More broadly, we expect currency markets to remain sensitive to relative growth, inflation, and central-bank dynamics, with country differentiation continuing to create opportunities across both developed and emerging markets.

Emerging Market Debt
(Overweight)
Emerging market sovereign and corporate debt remains an attractive opportunity, supported by elevated real yields, resilient income generation, and improving fundamentals in select countries. August saw a broad recovery in hard-currency spreads despite continued uncertainty around developed-market policy, reinforcing the asset class's carry appeal while also highlighting the importance of country and regional differentiation.

Carry and income remain central drivers of expected returns, though country selection is increasingly important given elevated dispersion. Recent performance continued to demonstrate that local political developments, policy decisions, and external balances can be more important than the broader global rates backdrop. We continue to favor markets where credible monetary frameworks, improving fundamentals, and supportive capital-flow dynamics provide a stronger foundation for returns.

Valuations remain attractive across select local- and hard-currency markets, while many EM currencies continue to offer compelling carry relative to developed markets. Higher global yields, persistent inflation, and geopolitical uncertainty remain important risks, but the broad tightening in sovereign and corporate spreads during August suggests that demand for income remains resilient. In an environment where global growth remains positive and default risks remain contained, we believe the asset class continues to offer attractive risk-adjusted return potential.

Corporate Credit
(Underweight Investment Grade (IG), small overweight high yield (HY))
We remain underweight investment grade corporates due to tight valuations and limited scope for broad-based spread compression. Investment grade spreads were notably stable in August despite meaningful repricing of the policy outlook, reinforcing the view that the market is increasingly dependent on technical demand and attractive all-in yields rather than further spread tightening. Carry therefore remains the principal source of expected return, while tight starting spreads leave limited scope for risk mitigation against renewed volatility.

Fundamentals remain solid, supported by healthy balance sheets, low downgrade risk, and generally resilient earnings. However, later-cycle pressures continue to build through elevated M&A activity, AI- and infrastructure-related capital expenditure, and higher shareholder distributions. AI-related financing remains an important driver of issuance, particularly among large technology and hyperscale issuers, reinforcing the need for greater selectivity as balance-sheet demands increase.

Regionally, we continue to prefer Europe over the U.S., supported by stronger technicals and resilient spread performance. Within the U.S., we favor financials and utilities over industrials and lower-quality non-financial issuers, where capex, M&A activity, and shareholder distributions may create greater balance-sheet pressure. We remain particularly selective in sectors where technological disruption or speculative financing activity could weaken credit quality.

We maintain a modest overweight to select high-yield issuers in both the U.S. and Europe. August's rally was concentrated in BB and single-B credits, while CCC-rated debt weakened, reinforcing our preference for higher-quality high yield rather than broad beta exposure. The divergence suggests that demand remains focused on carry and income in stronger credits rather than reflecting a generalized improvement in lower-quality fundamentals. We therefore continue to favor issuers with resilient cash flows, manageable refinancing needs, and less exposure to speculative or highly cyclical business models.

We continue to believe a meaningful demand-destruction scenario is not the base case. Low but positive economic growth, supported by fiscal spending, energy-related investment, and continued AI and infrastructure capex, remains consistent with a broadly benign default environment. However, with much of the good news already reflected in valuations, selectivity remains increasingly important.

Elevated dispersion across sectors, issuers, and ratings continues to create opportunities for active positioning. We favor businesses with resilient cash flows, strong pricing power, lower refinancing risk, and less exposure to cyclical demand pressure. While high-yield spreads leave limited margin for error, the yield per unit of spread-duration risk remains compelling relative to investment grade credit.

Leveraged Loans
(Neutral)
We maintain a neutral stance on leveraged loans as dispersion and prior spread widening have improved valuations across parts of the market. The asset class remains characterized by meaningful issuer-level differentiation, while CLO demand continues to provide an important source of technical support. Investor preference remains focused on higher-quality issuers and more resilient sectors, where current valuations provide better compensation for refinancing and macroeconomic risks.

Software and technology-linked issuers remain an area of caution given ongoing uncertainty around AI-related disruption. However, the broad-based selloff across parts of the sector has also created selective opportunities where market pricing appears disconnected from underlying fundamentals. We continue to favor higher-quality, mission-critical businesses with durable cash flows, proprietary data advantages, and high switching costs.

More broadly, elevated financing costs and persistent inflation uncertainty continue to pressure highly leveraged borrowers, even as overall corporate fundamentals remain relatively stable. The possibility of renewed central-bank tightening reinforces our preference for issuers with strong interest coverage, manageable maturity profiles, and durable cash-flow generation.

CLO issuance and demand for floating-rate exposure remain supportive, helping offset more mixed retail flows. While selectivity remains paramount, current valuations continue to provide improved, though still selective, compensation for refinancing and macroeconomic risks in higher-quality segments of the market.

Securitized Products
(Overweight)
Agency mortgage-backed securities and non-agency residential mortgage-backed securities (RMBS) remain a high-conviction overweight. Agency MBS benefited from the decline in rate volatility during August, with spreads tightening as the rates market became more orderly and mortgage rates eased modestly. We continue to view current-coupon agency MBS as attractive relative to other high-quality fixed income sectors, supported by compelling all-in yields, reduced prepayment risk, and improved relative value following the widening seen earlier in the summer.

Technical conditions remain broadly supportive, although the sector remains sensitive to changes in rate volatility. Attractive all-in yields continue to support demand from money managers, banks, and government-sponsored enterprises, while Federal Reserve balance-sheet runoff remains a source of supply. A renewed rise in volatility or a sharp move in the long end would remain the principal near-term risks, but August demonstrated the benefit of a more stable rates environment for agency MBS.

Non-agency RMBS continues to offer one of the more attractive opportunity sets within structured credit. Stable home prices, low loan-to-value ratios, improving collateral performance, and limited refinancing risk continue to support fundamentals. Strong issuance growth has been met with robust investor demand, particularly in residential credit sectors where recent vintages continue to demonstrate favorable performance characteristics.

Securitized credit remained broadly resilient during August. CMBS and ABS spreads moved only modestly, reinforcing the view that sector performance continues to be driven primarily by technical conditions and the rates-volatility backdrop rather than any meaningful deterioration in underlying collateral fundamentals.

Commercial mortgage-backed securities remain an attractive area of structured credit, though selectivity remains critical. Fundamentals are resilient in higher-quality segments, and strong technical demand continues to support the sector despite elevated financing costs. We continue to favor hospitality, logistics, storage, and high-quality multifamily assets, where operating performance and collateral quality remain comparatively strong.

Issuance across securitized markets, including CMBS, remains robust, but transactions have generally been well absorbed, reinforcing the strength of investor demand. Dispersion across property types, locations, and capital structures remains elevated, and we continue to focus on higher-quality transactions where collateral performance, borrower sponsorship, and cash-flow visibility provide stronger downside protection and risk mitigation.

Asset-backed securities remain supported by strong demand, attractive carry, and the sector's generally shorter-duration profile. Issuance has remained elevated, but demand for high-quality securitized collateral continues to help keep spreads contained. We continue to view the sector as a useful source of diversification and income in an environment where carry remains an important driver of returns.

We also continue to see opportunities in select non-consumer ABS where fundamentals remain stable and valuations remain attractive. We remain more cautious in areas where projected supply, technology disruption, or uncertain long-term economics are not adequately reflected in spreads.

Lastly, we remain constructive on Danish covered bonds, where defensive characteristics, strong legal frameworks, and attractive U.S. dollar-hedged yields continue to support relative value.

Broad Markets Fixed Income Team

Our team provides exposure to what we consider the best ideas in fixed income. Leveraging the expertise of our specialized teams, we use a team-based, rigorous and disciplined process that seeks out superior and repeatable results.

RISK CONSIDERATIONS
Diversification
neither assures a profit nor guarantees against loss in a declining market.

There is no assurance that a portfolio will achieve its investment objective. Portfolios are subject to market risk, which is the possibility that the market values of securities owned by the portfolio will decline and that the value of portfolio shares may therefore be less than what you paid for them. Market values can change daily due to economic and other events (e.g., natural disasters, health crises, terrorism, conflicts, and social unrest) that affect markets, countries, companies, or governments. It is difficult to predict the timing, duration, and potential adverse effects (e.g., portfolio liquidity) of events. Accordingly, you can lose money investing in a portfolio. Fixed-income securities are subject to the ability of an issuer to make timely principal and interest payments (credit risk), changes in interest rates (interest rate risk), the creditworthiness of the issuer and general market liquidity (market risk). In a rising interest-rate environment, bond prices may fall and may result in periods of volatility and increased portfolio redemptions. In a declining interest-rate environment, the portfolio may generate less income. Longer-term securities may be more sensitive to interest rate changes. Certain U.S. government securities purchased by the strategy, such as those issued by Fannie Mae and Freddie Mac, are not backed by the full faith and credit of the U.S. It is possible that these issuers will not have the funds to meet their payment obligations in the future. Public bank loans are subject to liquidity risk and the credit risks of lower-rated securities. High-yield securities (junk bonds) are lower-rated securities that may have a higher degree of credit and liquidity risk. Sovereign debt securities are subject to default risk. Mortgage- and asset-backed securities are sensitive to early prepayment risk and a higher risk of default and may be hard to value and difficult to sell (liquidity risk). They are also subject to credit, market, and interest rate risks. The currency market is highly volatile. Prices in these markets are influenced by, among other things, changing supply and demand for a particular currency; trade; fiscal, money and domestic or foreign exchange control programs and policies; and changes in domestic and foreign interest rates. Investments in foreign markets entail special risks such as currency, political, economic and market risks. The risks of investing in emerging market countries are greater than the risks generally associated with foreign investments. Derivative instruments may disproportionately increase losses and have a significant impact on performance. They also may be subject to counterparty, liquidity, valuation, and correlation and market risks. Restricted and illiquid securities may be more difficult to sell and value than publicly traded securities (liquidity risk). Due to the possibility that prepayments will alter the cash flows on collateralized mortgage obligations (CMOs), it is not possible to determine in advance their final maturity date or average life. In addition, if the collateral securing the CMOs or any third-party guarantees are insufficient to make payments, the portfolio could sustain a loss.

DEFINITIONS
Basis point (bp): One basis point = 0.01%.


INDEX DEFINITIONS
The indexes shown in this report are not meant to depict the performance of any specific investment, and the indexes shown do not include any expenses, fees, or sales charges, which would lower performance. The indexes shown are unmanaged and should not be considered an investment. It is not possible to invest directly in an index.

“Bloomberg®” and the Bloomberg Index/Indices used are service marks of Bloomberg Finance L.P. and its affiliates and have been licensed for use for certain purposes by Morgan Stanley Investment Management (MSIM). Bloomberg is not affiliated with MSIM, does not approve, endorse, review, or recommend any product, and. does not guarantee the timeliness, accurateness, or completeness of any data or information relating to any product.

The Bloomberg Euro Aggregate Corporate Index (Bloomberg Euro IG Corporate) is an index designed to reflect the performance of the euro-denominated investment-grade corporate bond market.

The Bloomberg Global Aggregate Corporate Index is the corporate component of the Bloomberg Global Aggregate index, which provides a broad-based measure of the global investment-grade fixed income markets.

The Bloomberg US Corporate High Yield Index measures the market of USD-denominated, non-investment grade, fixed-rate, taxable corporate bonds. Securities are classified as high yield if the middle rating of Moody’s, Fitch, and S&P is Ba1/BB+/BB+ or below. The index excludes emerging market debt.

The Bloomberg US Corporate Index is a broad-based benchmark that measures the investment grade, fixed-rate, taxable, corporate bond market.

The Bloomberg US Mortgage-Backed Securities (MBS) Index tracks agency mortgage-backed pass-through securities (both fixed-rate and hybrid ARM) guaranteed by Ginnie Mae (GNMA), Fannie Mae (FNMA) and Freddie Mac (FHLMC). The index is constructed by grouping individual TBA-deliverable MBS pools into aggregates or generics based on program, coupon, and vintage. Introduced in 1985, the GNMA, FHLMC and FNMA fixed-rate indexes for 30- and 15-year securities were backdated to January 1976, May 1977, and November 1982, respectively. In April 2007, agency hybrid adjustable-rate mortgage (ARM) pass-through securities were added to the index.


Consumer Price Index (CPI) is a measure that examines the weighted average of prices of a basket of consumer goods and services, such as transportation, food, and medical care.

Euro vs. USD—Euro total return versus U.S. dollar.


German 10YR bonds—Germany Benchmark 10-Year Datastream Government Index; Japan 10YR government bonds —Japan Benchmark 10-Year Datastream Government Index; and 10YR US Treasury—US Benchmark 10-Year Datastream Government Index.

The ICE BofAML European Currency High-Yield Constrained Index (ICE BofAML Euro HY constrained) is designed to track the performance of euro- and British pound sterling-denominated below investment-grade corporate debt publicly issued in the Eurobond, sterling.

The ICE BofAML US Mortgage-Backed Securities (ICE BofAML US Mortgage Master) Index tracks the performance of US dollar-denominated, fixed-rate and hybrid residential mortgage pass-through securities publicly issued by US agencies in the US domestic market.

The ICE BofAML US High Yield Master II Constrained Index (ICE BofAML US High Yield) is a market value-weighted index of all domestic and Yankee high-yield bonds, including deferred-interest bonds and payment-in-kind securities. Its securities have maturities of one year or more and a credit rating lower than BBB-/Baa3 but are not in default.

The ISM Manufacturing Index is based on surveys of more than 300 manufacturing firms by the Institute of Supply Management. The ISM Manufacturing Index monitors employment, production inventories, new orders, and supplier deliveries. A composite diffusion index is created that monitors conditions in national manufacturing based on the data from these surveys.

Italy 10-Year Government Bonds—Italy Benchmark 10-Year Datastream Government Index.

The JP Morgan CEMBI Broad Diversified Index is a global, liquid corporate emerging markets benchmark that tracks US-denominated corporate bonds issued by emerging markets entities.

The JPMorgan Government Bond Index—emerging markets (JPM local EM debt) tracks local currency bonds issued by emerging market governments. The index is positioned as the investable benchmark that includes only those countries that are accessible by most of the international investor base (excludes China and India as of September 2013).

The JPMorgan Government Bond Index Emerging Markets (JPM External EM Debt) tracks local currency bonds issued by emerging market governments. The index is positioned as the investable benchmark that includes only those countries that are accessible by most of the international investor base (excludes China and India as of September 2013).

The JP Morgan Emerging Markets Bond Index Global (EMBI Global) tracks total returns for traded external debt instruments in the emerging markets and is an expanded version of the EMBI+. As with the EMBI+, the EMBI Global includes US dollar-denominated Brady bonds, loans, and Eurobonds with an outstanding face value of at least $500 million.

The JP Morgan GBI-EM Global Diversified Index is a market-capitalization weighted, liquid global benchmark for US-dollar corporate emerging market bonds representing Asia, Latin America, Europe, and the Middle East/Africa.

JPY vs. USD—Japanese yen total return versus US dollar.

The Markit ITraxx Europe Index comprises 125 equally weighted credit default swaps on investment grade European corporate entities, distributed among 4 sub-indices: Financials (Senior & Subordinated), Non-Financials and HiVol.

The Nikkei 225 Index (Japan Nikkei 225) is a price-weighted index of Japan’s top 225 blue-chip companies on the Tokyo Stock Exchange.

The MSCI AC Asia ex-Japan Index (MSCI Asia ex-Japan) captures large- and mid-cap representation across two of three developed markets countries (excluding Japan) and eight emerging markets countries in Asia.

The MSCI All Country World Index (ACWI, MSCI global equities) is a free float-adjusted market capitalization weighted index designed to measure the equity market performance of developed and emerging markets. The term "free float" represents the portion of shares outstanding that are deemed to be available for purchase in the public equity markets by investors. The performance of the Index is listed in US dollars and assumes reinvestment of net dividends.

MSCI Emerging Markets Index (MSCI emerging equities) captures large- and mid-cap representation across 23 emerging markets (EM) countries.

The MSCI World Index (MSCI developed equities) captures large and mid-cap representation across 23 developed market (DM) countries.

Purchasing Managers Index (PMI) is an indicator of the economic health of the manufacturing sector.

The Refinitiv Convertible Global Focus USD Hedged Index is a market weighted index with a minimum size for inclusion of $500 million (US), 200 million (Europe), 22 billion Yen, and $275 million (Other) of Convertible Bonds with an Equity Link.

The Russell 2000® Index is an index that measures the performance of the 2,000 smallest companies in the Russell 3000 Index.

The S&P 500® Index (US S&P 500) measures the performance of the large-cap segment of the US equities market, covering approximately 75 percent of the US equities market. The index includes 500 leading companies in leading industries of the U.S. economy.

S&P CoreLogic Case-Shiller US National Home Price NSA Index seeks to measure the value of residential real estate in 20 major US metropolitan areas: Atlanta, Boston, Charlotte, Chicago, Cleveland, Dallas, Denver, Detroit, Las Vegas, Los Angeles, Miami, Minneapolis, New York, Phoenix, Portland, San Diego, San Francisco, Seattle, Tampa and Washington, D.C.

The S&P/LSTA US Leveraged Loan 100 Index (S&P/LSTA Leveraged Loan Index) is designed to reflect the performance of the largest facilities in the leveraged loan market.


The S&P GSCI Copper Index (Copper), a sub-index of the S&P GSCI, provides investors with a reliable and publicly available benchmark for investment performance in the copper commodity market.

The S&P GSCI Softs (GSCI soft commodities) Index is a sub-index of the S&P GSCI that measures the performance of only the soft commodities, weighted on a world production basis. In 2012, the S&P GSCI Softs Index included the following commodities: coffee, sugar, cocoa, and cotton.


Spain 10-Year Government Bonds—Spain Benchmark 10-Year Datastream Government Index.

The Thomson Reuters Convertible Global Focus USD Hedged Index is a market weighted index with a minimum size for inclusion of $500 million (US), 200 million euro (Europe), 22 billion yen, and $275 million (Other) of convertible bonds with an equity link.


U.K. 10YR government bonds—U.K. Benchmark 10-Year Datastream Government Index. For the following Datastream government bond indexes, benchmark indexes are based on single bonds. The bond chosen for each series is the most representative bond available for the given maturity band at each point in time. Benchmarks are selected according to the accepted conventions within each market. Generally, the benchmark bond is the latest issue within the given maturity band; consideration is also given to yield, liquidity, issue size and coupon.

The US Dollar Index (DXY) is an index of the value of the United States dollar relative to a basket of foreign currencies, often referred to as a basket of US trade partners’ currencies.

The Chicago Board Options Exchange (CBOE) Market Volatility (VIX) Index shows the market’s expectation of 30-day volatility.

There is no guarantee that any investment strategy will work under all market conditions, and each investor should evaluate their ability to invest for the long-term, especially during periods of downturn in the market.


A separately managed account may not be appropriate for all investors. Separate accounts managed according to the particular strategy may include securities that may not necessarily track the performance of a particular index. Please consider the investment objectives, risks and fees of the Strategy carefully before investing. A minimum asset level is required. For important information about the investment managers, please refer to Form ADV Part 2.

The views and opinions and/or analysis expressed are those of the author or the investment team as of the date of preparation of this material and are subject to change at any time without notice due to market or economic conditions and may not necessarily come to pass. Furthermore, the views will not be updated or otherwise revised to reflect information that subsequently becomes available or circumstances existing, or changes occurring, after the date of publication. The views expressed do not reflect the opinions of all investment personnel at Morgan Stanley Investment Management (MSIM) and its subsidiaries and affiliates (collectively “the Firm”) and may not be reflected in all the strategies and products that the Firm offers.

Forecasts and/or estimates provided herein are subject to change and may not actually come to pass. Information regarding expected market returns and market outlooks is based on the research, analysis and opinions of the authors or the investment team. These conclusions are speculative in nature, may not come to pass and are not intended to predict the future performance of any specific strategy or product the Firm offers. Future results may differ significantly depending on factors such as changes in securities or financial markets or general economic conditions.

This material has been prepared on the basis of publicly available information, internally developed data and other third-party sources believed to be reliable. However, no assurances are provided regarding the reliability of such information and the Firm has not sought to independently verify information taken from public and third-party sources.

This material is a general communication, which is not impartial, and all information provided has been prepared solely for informational and educational purposes and does not constitute an offer or a recommendation to buy or sell any particular security or to adopt any specific investment strategy. The information herein has not been based on a consideration of any individual investor circumstances and is not investment advice, nor should it be construed in any way as tax, accounting, legal or regulatory advice. To that end, investors should seek independent legal and financial advice, including advice as to tax consequences, before making any investment decision.

Charts and graphs provided herein are for illustrative purposes only. Past performance is no guarantee of future results.

The indexes are unmanaged and do not include any expenses, fees, or sales charges. It is not possible to invest directly in an index. Any index referred to herein is the intellectual property (including registered trademarks) of the applicable licensor. Any product based on an index is in no way sponsored, endorsed, sold, or promoted by the applicable licensor and it shall not have any liability with respect thereto.

This material is not a product of Morgan Stanley’s Research Department and should not be regarded as a research material or a recommendation.

The Firm has not authorized financial intermediaries to use and to distribute this material unless such use and distribution is made in accordance with applicable law and regulation. Additionally, financial intermediaries are required to satisfy themselves that the information in this material is appropriate for any person to whom they provide this material in view of that person’s circumstances and purpose. The Firm shall not be liable for, and accepts no liability for, the use or misuse of this material by any such financial intermediary.

This material may be translated into other languages. Where such a translation is made this English version remains definitive. If there are any discrepancies between the English version and any version of this material in another language, the English version shall prevail.

The whole or any part of this material may not be directly or indirectly reproduced, copied, modified, used to create a derivative work, performed, displayed, published, posted, licensed, framed, distributed, or transmitted or any of its contents disclosed to third parties without the Firm’s express written consent. This material may not be linked to unless such hyperlink is for personal and non-commercial use. All information contained herein is proprietary and is protected under copyright and other applicable law.

Eaton Vance is part of Morgan Stanley Investment Management. Morgan Stanley Investment Management is the asset management division of Morgan Stanley.

DISTRIBUTION
This material is only intended for and will only be distributed to persons resident in jurisdictions where such distribution or availability would not be contrary to local laws or regulations.

MSIM, the asset management division of Morgan Stanley (NYSE: MS), and its affiliates have arrangements in place to market each other’s products and services. Each MSIM affiliate is regulated as appropriate in the jurisdiction it operates. MSIM’s affiliates are: Calvert Research and Management, Eaton Vance Management, Parametric Portfolio Associates LLC, Parametric SAS, and Atlanta Capital Management LLC.

This material has been issued by any one or more of the following entities:


EMEA:
This material is for Professional Clients/Accredited Investors only.

In the EU, MSIM materials are issued by MSIM Fund Management (Ireland) Limited (“FMIL”). FMIL is regulated by the Central Bank of Ireland and is incorporated in Ireland as a private company limited by shares with company registration number 616661 and has its registered address at 24-26 City Quay, Dublin 2, DO2 NY19, Ireland.

Outside the EU, MSIM materials are issued by Morgan Stanley Investment Management Limited (MSIM Ltd) is authorised and regulated by the Financial Conduct Authority. Registered in England. Registered No. 1981121. Registered Office: 25 Cabot Square, Canary Wharf, London E14 4QA.

In Switzerland, MSIM materials are issued by Morgan Stanley & Co. International plc, London (Zurich Branch) Authorised and regulated by the Eidgenössische Finanzmarktaufsicht ("FINMA"). Registered Office: Beethovenstrasse 33, 8002 Zurich, Switzerland.

Italy: MSIM FMIL (Milan Branch), (Sede Secondaria di Milano) Palazzo Serbelloni Corso Venezia, 16 20121 Milano, Italy. The Netherlands: MSIM FMIL (Amsterdam Branch), Rembrandt Tower, 11th Floor Amstelplein 1 1096HA, Netherlands. France: MSIM FMIL (Paris Branch), 61 rue de Monceau 75008 Paris, France. Spain: MSIM FMIL (Madrid Branch), Calle Serrano 55, 28006, Madrid, Spain. Germany: MSIM FMIL Frankfurt Branch, Große Gallusstraße 18, 60312 Frankfurt am Main, Germany (Gattung: Zweigniederlassung (FDI) gem. § 53b KWG). Denmark: MSIM FMIL (Copenhagen Branch), Gorrissen Federspiel, Axel Towers, Axeltorv2, 1609 Copenhagen V, Denmark. show less

MIDDLE EAST
Dubai International Financial Centre:
This information does not constitute or form part of any offer to issue or sell, or any solicitation of any offer to subscribe for or purchase, any securities or investment products in the UAE (including the Dubai International Financial Centre and the Abu Dhabi Global Market) and accordingly should not be construed as such. Furthermore, this information is being made available on the basis that the recipient acknowledges and understands that the entities and securities to which it may relate have not been approved, licensed by or registered with the UAE Central Bank, the Dubai Financial Services Authority, the UAE Securities and Commodities Authority, the Financial Services Regulatory Authority or any other relevant licensing authority or government agency in the UAE. The content of this report has not been approved by or filed with the UAE Central Bank, the Dubai Financial Services Authority, the UAE Securities and Commodities Authority or the Financial Services Regulatory Authority.

Abu Dhabi Global Market ("ADGM"): This material is sent strictly within the context of, and constitutes, an Exempt Communication. This material relates to strategies which are not subject to any form of regulation or approval by the Financial Services Regulatory Authority of the Abu Dhabi Global Market (the “FSRA”).


Saudi Arabia
This financial promotion was issued and approved for use in Saudi Arabia by Morgan Stanley Saudi Arabia, Al Rashid Tower, Kings Sand Street, Riyadh, Saudi Arabia, authorized and regulated by the Capital Market Authority license number 06044-37.


US
NOT FDIC INSURED | OFFER NO BANK GUARANTEE | MAY LOSE VALUE | NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY | NOT A DEPOSIT


Latin America (Brazil, Chile Colombia, Mexico, Peru, and Uruguay)
This material is for use with an institutional investor or a qualified investor only. All information contained herein is confidential and is for the exclusive use and review of the intended addressee and may not be passed on to any third party. This material is provided for informational purposes only and does not constitute a public offering, solicitation, or recommendation to buy or sell for any product, service, security and/or strategy. A decision to invest should only be made after reading the strategy documentation and conducting in-depth and independent due diligence.


ASIA PACIFIC
Hong Kong:
This material is disseminated by Morgan Stanley Asia Limited for use in Hong Kong and shall only be made available to “professional investors” as defined under the Securities and Futures Ordinance of Hong Kong (Cap 571). The contents of this material have not been reviewed nor approved by any regulatory authority including the Securities and Futures Commission in Hong Kong. Accordingly, save where an exemption is available under the relevant law, this material shall not be issued, circulated, distributed, directed at, or made available to, the public in Hong Kong. Singapore: This material is disseminated in Singapore by Morgan Stanley Investment Management Company, Registration No. 199002743C. This material should not be considered to be the subject of an invitation for subscription or purchase, whether directly or indirectly, to the public or any member of the public in Singapore other than (i) to an institutional investor under section 304 of the Securities and Futures Act, Chapter 289 of Singapore (“SFA”), (ii) to a “relevant person” (which includes an accredited investor) pursuant to section 305 of the SFA, and such distribution is in accordance with the conditions specified in section 305 of the SFA; or (iii) otherwise pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. This material has not been reviewed by the Monetary Authority of Singapore. Australia: This material is provided by Morgan Stanley Investment Management (Australia) Pty Ltd ABN 22122040037, AFSL No. 314182 and its affiliates and does not constitute an offer of interests. Morgan Stanley Investment Management (Australia) Pty Limited arranges for MSIM affiliates to provide financial services to Australian wholesale clients. Interests will only be offered in circumstances under which no disclosure is required under the Corporations Act 2001 (Cth) (the “Corporations Act”). Any offer of interests will not purport to be an offer of interests in circumstances under which disclosure is required under the Corporations Act and will only be made to persons who qualify as a “wholesale client” (as defined in the Corporations Act). This material will not be lodged with the Australian Securities and Investments Commission.


Japan:
For professional investors, this material is circulated or distributed solely for informational purposes. For non-professional investors, this material is provided in connection with Morgan Stanley Investment Management (Japan) Co., Ltd. (“MSIMJ”)’s business with respect to discretionary investment management agreements (“IMA”) and investment advisory agreements (“IAA”). This does not constitute a recommendation or solicitation of transactions nor offers any particular financial instruments. Under an IMA, with respect to the management of client assets, the client prescribes basic management policies in advance and commissions MSIMJ to make all investment decisions based on an analysis of the value, etc. of the securities, and MSIMJ accepts such commission. The client shall delegate to MSIMJ the authorities necessary to make such investment decisions. MSIMJ exercises these delegated authorities accordingly, and the client shall not make individual instructions. All investment profits and losses belong to the clients; principal is not guaranteed. Please consider the investment objectives and nature of risks before investing. As an investment advisory fee for an IAA or an IMA, the amount of assets subject to the contract multiplied by a certain rate (the upper limit is 2.20% per annum (including tax)) shall be incurred in proportion to the contract period. For some strategies, a contingency fee may be incurred in addition to the fee mentioned above. Indirect charges also may be incurred, such as brokerage commissions for underlying securities. Since these charges and expenses vary by contract and other factors, MSIMJ cannot present the rates, upper limits, etc. in advance. All clients should read thoroughly the Documents Provided Prior to the Conclusion of a Contract carefully before executing an agreement. This material is distributed in Japan by MSIMJ, Registered No. 410 (Director of Kanto Local Finance Bureau (Financial Instruments Firms)), Membership: the Japan Securities Dealers Association, the Investment Management Association of Japan and the Type II Financial Instruments Firms Association.