 Top


Natural resource equities may appear to offer an alternative to commodity futures, but their returns reflect company-specific and broader equity-market factors. We explore why the two exposures can behave differently and what that means for portfolio diversification and inflation protection.
The sharp rise in energy prices in 2026 has renewed inflation concerns and prompted investors to revisit commodity allocations. Broad, liquid commodity exposure is generally obtained through futures-based strategies, but natural resource equities may appear to offer a simpler, more familiar alternative. This reasoning is understandable: producers’ revenues are often linked to the commodities they sell. Yet producer equities also reflect costs, capital allocation, company-specific risks and broad equity-market conditions. As a result, their inflation sensitivity and diversification properties can differ materially from those of commodity futures.
Different assets, different return drivers
It may seem puzzling that a natural resource company’s shares can behave differently from the underlying commodity. Why wouldn’t the price of copper, for instance, be the main driver of a copper producer’s stock? We would argue that several fundamental differences can cause their returns to diverge.
First, company-specific factors may affect a stock price without necessarily affecting the commodity price. Changes in dividend policy, corporate governance or earnings potential may influence a company’s stock price without any associated impact on the underlying commodity. The 2010 Deepwater Horizon disaster illustrates the distinction. BP’s shares fell sharply as investors reassessed the company’s cleanup costs, legal liabilities, operational risks and balance sheet pressures. BP later suspended its dividend. Broad crude oil futures did not experience a comparable BP-specific decline. The episode shows how an event can materially impair a producer’s value without having the same effect on the price of its commodity.
Second, market-level factors that affect equity prices aren’t necessarily reflected in commodity prices. These factors, often grouped generically as equity beta, include changes in earnings multiples, the regulatory environment and the tendency for stocks to move together. The substantial divergence between returns on energy futures and energy stocks in 2026 offers a timely example. Through Sept. 30, 2026, the Bloomberg Petroleum Subindex, a futures-based index of crude oil and refined petroleum products, surged nearly +130% year-to-date, while the S&P 500 Energy Index returned just +40%. Even during a strong commodity rally, natural resource equities may capture only part of the commodity’s gains.
Third, a company’s business model can dampen, delay or sometimes amplify its sensitivity to commodity prices. Hedging policies, long-term sales contracts, production volumes, operating costs, product mix and downstream operations all affect how changes in the underlying commodity prices flow through to revenue and earnings. These practices vary widely by company and industry, further limiting the extent to which commodity-related equities behave like direct futures exposure.
These differences matter because investors generally add commodities to a portfolio for a specific purpose, often to hedge inflation or increase diversification, rather than simply to express a view on resource companies
Different exposures, different portfolio outcomes
For many investors, the appeal of commodities lies in their potential to hedge inflation and diversify a portfolio. These benefits may be diminished when exposure comes through publicly traded equities rather than commodity futures. Over the last 20 years, natural resource equities exhibited a lower correlation with changes in the Consumer Price Index (CPI) than the broad Bloomberg Commodity Index Total Return futures index—0.33 versus 0.60. While these correlations are sample-dependent, they are consistent with the broader point that producer equities carry substantial corporate and equity-market exposures in addition to commodity-price exposure.
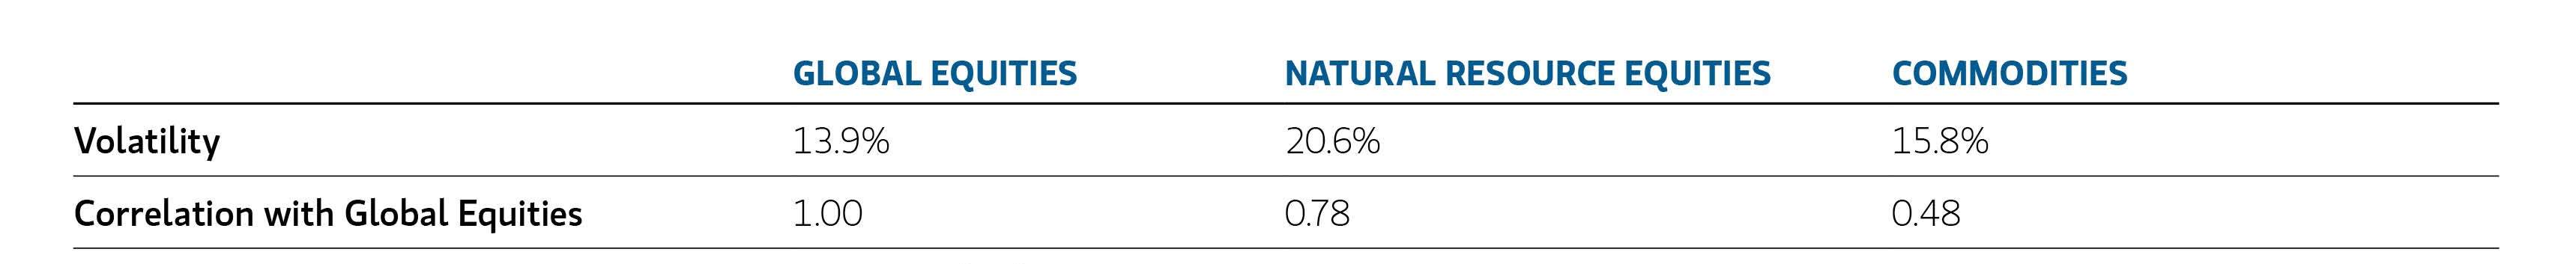
Natural resource equities also have tended to exhibit higher volatility and higher correlation with equities than commodities have.
Volatility and equity correlation: Commodities vs. natural resource equities (Jan. 2006 – Dec. 2025)
Sources: MSCI, S&P Dow Jones, Bloomberg, Parametric, 09/30/2026. For illustrative purposes only. Not a recommendation to buy or sell any security. It is not possible to invest directly in an index. Volatility as measured by standard deviation. Global Equities volatility and correlation measures are represented by the MSCI ACWI Net Total Return Local Index; Natural Resource Equities by the S&P Global Natural Resources Net Total Return Index; and Commodities by the Bloomberg Commodity Index Total Return.
Volatility and equity correlation: Commodities vs. natural resource equities (Jan. 2006 – Dec. 2025)
Because natural resource equities have historically exhibited greater volatility and higher correlation with equity markets, an allocation to them may provide less portfolio diversification than a similarly sized allocation to broad commodity futures.
The bottom line
Natural resource equities can play a useful role for investors seeking exposure to commodity-related businesses and their long-term earnings potential. But they should not be assumed to provide the same exposure as commodity futures. Their returns also reflect operating costs, management decisions, balance-sheet risk, valuation changes and broad equity-market movements. For investors whose primary objective is to hedge inflation or gain diversification from equities, a futures-based commodity allocation may be a more direct tool. The two exposures are related, but they are not interchangeable.
Definitions:
Correlation is a statistic that describes the size and direction of a relationship between variables, measured by a coefficient ranging from -1 to +1 indicating a stronger negative or positive relationship.

Risk Considerations
Trading in, and investment exposure to, the commodities markets may involve substantial risks and subject the Portfolio to greater volatility. In general, equity securities' values also fluctuate in response to activities specific to a company.
The views expressed in these posts are those of the authors and are current only through the date stated. These views are subject to change at any time based upon market or other conditions, and Parametric and its affiliates disclaim any responsibility to update such views. These views may not be relied upon as investment advice and, because investment decisions for Parametric are based on many factors, may not be relied upon as an indication of trading intent on behalf of any Parametric strategy. The discussion herein is general in nature and is provided for informational purposes only. There is no guarantee as to its accuracy or completeness. Past performance is no guarantee of future results. All investments are subject to the risk of loss. Prospective investors should consult with a tax or legal advisor before making any investment decision. Please refer to the Disclosure page on our website for important information about investments and risks.
DISTRIBUTION
This material is only intended for and will only be distributed to persons resident in jurisdictions where such distribution or availability would not be contrary to local laws or regulations.
MSIM, the asset management division of Morgan Stanley (NYSE: MS), and its affiliates have arrangements in place to market each other’s products and services. Each MSIM affiliate is regulated as appropriate in the jurisdiction it operates. MSIM’s affiliates are: Eaton Vance Management (International) Limited, Eaton Vance Advisers International Ltd, Calvert Research and Management, Eaton Vance Management, Parametric Portfolio Associates LLC, and Atlanta Capital Management LLC.
This material has been issued by any one or more of the following entities:
EMEA:
This material is for Professional Clients/Accredited Investors only.
In the EU, MSIM and Eaton Vance materials are issued by MSIM Fund Management (Ireland) Limited (“FMIL”). FMIL is regulated by the Central Bank of Ireland and is incorporated in Ireland as a private company limited by shares with company registration number 616661 and has its registered address at 24-26 City Quay, Dublin 2, D02 NY 19, Ireland.
Outside the EU, MSIM materials are issued by Morgan Stanley Investment Management Limited (MSIM Ltd) is authorised and regulated by the Financial Conduct Authority. Registered in England. Registered No. 1981121. Registered Office: 25 Cabot Square, Canary Wharf, London E14 4QA.
In Switzerland, MSIM materials are issued by Morgan Stanley & Co. International plc, London (Zurich Branch) Authorised and regulated by the Eidgenössische Finanzmarktaufsicht ("FINMA"). Registered Office: Beethovenstrasse 33, 8002 Zurich, Switzerland.
Outside the US and EU, Eaton Vance materials are issued by Eaton Vance Management (International) Limited (“EVMI”) 125 Old Broad Street, London, EC2N 1AR, UK, which is authorised and regulated in the United Kingdom by the Financial Conduct Authority.
Italy: MSIM FMIL (Milan Branch), (Sede Secondaria di Milano) Palazzo Serbelloni Corso Venezia, 16 20121 Milano, Italy. The Netherlands: MSIM FMIL (Amsterdam Branch), Rembrandt Tower, 11th Floor Amstelplein 1 1096HA, Netherlands. France: MSIM FMIL (Paris Branch), 61 rue de Monceau 75008 Paris, France. Spain: MSIM FMIL (Madrid Branch), Calle Serrano 55, 28006, Madrid, Spain. Germany: Germany: MSIM FMIL (Frankfurt Branch), Grosse Gallusstrasse 18, 60312 Frankfurt am Main, Germany (Gattung: Zweigniederlassung (FDI) gem. § 53b KWG). Denmark: MSIM FMIL (Copenhagen Branch), Gorrissen Federspiel, Axel Towers, Axeltorv2, 1609 Copenhagen V, Denmark.
MIDDLE EAST
Dubai: MSIM Ltd (Representative Office, Unit Precinct 3-7th Floor-Unit 701 and 702, Level 7, Gate Precinct Building 3, Dubai International Financial Centre, Dubai, 506501, United Arab Emirates. Telephone: +97 (0)14 709 7158). This document is distributed in the Dubai International Financial Centre by Morgan Stanley Investment Management Limited (Representative Office), an entity regulated by the Dubai Financial Services Authority (“DFSA”). It is intended for use by professional clients and market counterparties only. This document is not intended for distribution to retail clients, and retail clients should not act upon the information contained in this document.
This document relates to a financial product which is not subject to any form of regulation or approval by the DFSA. The DFSA has no responsibility for reviewing or verifying any documents in connection with this financial product. Accordingly, the DFSA has not approved this document or any other associated documents nor taken any steps to verify the information set out in this document and has no responsibility for it. The financial product to which this document relates may be illiquid and/or subject to restrictions on its resale or transfer. Prospective purchasers should conduct their own due diligence on the financial product. If you do not understand the contents of this document, you should consult an authorized financial adviser.
Latin America (Brazil, Chile Colombia, Mexico, Peru, and Uruguay)
This material is for use with an institutional investor or a qualified investor only. All information contained herein is confidential and is for the exclusive use and review of the intended addressee and may not be passed on to any third party. This material is provided for informational purposes only and does not constitute a public offering, solicitation, or recommendation to buy or sell for any product, service, security and/or strategy. A decision to invest should only be made after reading the strategy documentation and conducting in-depth and independent due diligence.
ASIA PACIFIC
Hong Kong: This material is disseminated by Morgan Stanley Asia Limited for use in Hong Kong and shall only be made available to “professional investors” as defined under the Securities and Futures Ordinance of Hong Kong (Cap 571). The contents of this material have not been reviewed nor approved by any regulatory authority including the Securities and Futures Commission in Hong Kong. Accordingly, save where an exemption is available under the relevant law, this material shall not be issued, circulated, distributed, directed at, or made available to, the public in Hong Kong.
Singapore: This material is disseminated by Morgan Stanley Investment Management Company and may not be circulated or distributed, whether directly or indirectly, to persons in Singapore other than to (i) an accredited investor (ii) an expert investor or (iii) an institutional investor as defined in Section 4A of the Securities and Futures Act, Chapter 289 of Singapore (“SFA”); or (iv) otherwise pursuant to, and in accordance with the conditions of, any other applicable provision of the SFA. This publication has not been reviewed by the Monetary Authority of Singapore.
Australia: This material is provided by Morgan Stanley Investment Management (Australia) Pty Ltd ABN 22122040037, AFSL No. 314182 and its affiliates and does not constitute an offer of interests. Morgan Stanley Investment Management (Australia) Pty Limited arranges for MSIM affiliates to provide financial services to Australian wholesale clients. Interests will only be offered in circumstances under which no disclosure is required under the Corporations Act 2001 (Cth) (the “Corporations Act”). Any offer of interests will not purport to be an offer of interests in circumstances under which disclosure is required under the Corporations Act and will only be made to persons who qualify as a “wholesale client” (as defined in the Corporations Act). This material will not be lodged with the Australian Securities and Investments Commission.


