
 Top

August was defined by divergence within developed-market yield curves rather than a broad directional move in rates. Short-dated yields rose as investors reassessed the likelihood that the policy cycle could shift back toward tightening, while long-dated yields were stable or lower, leaving curves flatter across most major markets. Spread sectors were firm but increasingly dispersed: high yield and emerging market debt tightened materially, while investment grade was largely unchanged. Volatility also declined across both rates and equities.
The rates move was relatively contained in the U.S. The 10-year Treasury yield rose 1.5 basis points (bps) to 4.75%, while the 2-year yield increased 5bps and the 30-year declined 3bps, flattening both the 2s10s and 5s30s curves. Ten-year breakevens widened 4bps as real yields declined, suggesting that the modest increase in nominal yields was driven more by inflation compensation than by tighter real rates. Elsewhere, moves were more pronounced and largely country-specific. Ten-year yields rose 17bps in Australia, 15bps in Japan, and 12bps in Germany, while UK gilt yields were broadly unchanged. Japanese yields reached their highest levels since the mid-1990s, reflecting expectations for further Bank of Japan tightening alongside concerns around fiscal expansion.
Federal Reserve communication was the central policy event of the month. Following the late-July decision to leave rates unchanged at 3.50%-3.75%, despite three votes for a 25bps hike, markets entered August with a September increase close to fully priced. Expectations eased following a softer July Consumer Price Index (CPI) report, then rose again after Chair Warsh's Jackson Hole address reaffirmed the Fed's 2% personal consumption expenditures (PCE) inflation target, characterized financial conditions as insufficiently restrictive, and emphasized the need for further progress on underlying inflation. With PCE inflation at 3.7%, the message was viewed as notably firmer than in July. September hike expectations moved back above one-half, while the long end remained relatively stable. Neither the European Central Bank nor the Bank of England met during the month.
Foreign exchange markets extended July's reversal of U.S. dollar strength, with the broad dollar index declining 0.9%. Commodity and higher-beta currencies generally outperformed, with the Korean won, South African rand, Australian dollar, and Mexican peso all appreciating. The yen was the weakest major currency, depreciating 1.5% despite higher Japanese yields. Emerging-market currency performance remained highly differentiated, with the Brazilian real and Colombian peso weakening against a broadly softer dollar.
Credit markets were notably stable at the top of the capital structure. U.S. investment grade spreads finished unchanged at 78bps option-adjusted spread (OAS), while Euro investment grade remained at 79bps. Shorter maturities modestly outperformed longer-duration credit in both markets, while sector dispersion largely offset at the index level. Sterling credit was the exception, tightening 3bps to 86bps. The limited spread movement reflected a balance between robust corporate fundamentals and strong technical demand on one side, and continued supply from M&A activity and AI-related capital expenditure on the other. Strong Q2 earnings helped reinforce the underlying fundamental backdrop, but with spreads already close to cycle tights, carry and roll rather than further compression remained the dominant sources of return.
High yield delivered the strongest spread performance of the month, though dispersion remained pronounced. U.S. high yield tightened 18bps to 261bps and Euro high yield tightened 12bps to 260bps. The move was concentrated in higher-quality cohorts, with BB and single-B credits leading, while CCC-rated debt widened 32bps in the U.S. and by a similar amount in Europe. The divergence suggested continued demand for carry in stronger credits rather than a broad-based improvement in lower-quality fundamentals. AI and data-center financing also remained an important feature of primary issuance, reinforcing the need for selectivity within newer and more capital-intensive areas of the market.
Leveraged loans generated solid returns during August, supported by carry, modest price appreciation, and continued collateralized loan obligation (CLO) demand. The asset class returned approximately 93bps during the month, with roughly one-third of the return coming from price appreciation. Performance remained highly differentiated, however, with software continuing to lag the broader market amid persistent concerns around AI-related disruption. Outside software, loan prices were comparatively stable, while robust CLO creation continued to provide an important source of technical demand.
Securitized markets benefited from lower rate volatility and increasingly supportive mortgage technicals. Agency mortgage-backed securities (MBS) spreads tightened 4bps to approximately 112bps versus comparable Treasuries as implied rate volatility declined. Elevated mortgage rates also reduced refinancing activity, while slower seasonal issuance helped constrain new agency supply. Mortgage rates remained elevated during the month but eased to 6.66% by month-end. Securitized credit moved only modestly, with BBB commercial mortgage-backed securities (CMBS) tightening slightly and AAA asset-backed securities (ABS) finishing somewhat wider. The combination of lower volatility and tighter supply provided support without requiring a material improvement in underlying credit fundamentals.
Emerging markets (EM) outperformed, reversing July's widening. External sovereign spreads tightened 10bps to 217bps and EM corporate spreads tightened 11bps to 199bps, with gains broad across regions and ratings. The Middle East, which had underperformed in July, tightened 13bps as regional risk premia compressed. Local markets remained highly differentiated, with yields falling materially in Indonesia and Brazil while rising in Poland and Mexico. Policy easing also continued selectively, including 25bps cuts in both Brazil and Hungary. The rally left credit valuations at very tight levels across several parts of the asset class, reinforcing the importance of local rates, currencies, and country-specific opportunities rather than broad spread exposure.
Overall, August reversed several of July's dominant market moves: curves flattened after steepening, Federal Reserve communication was interpreted as more hawkish, spread sectors recovered, and volatility declined. What remained consistent was the persistence of dispersion across ratings, regions, and sectors. With spreads still near historically tight levels and the policy outlook increasingly skewed toward renewed tightening, carry, relative value, and active security selection remained the primary drivers of excess return.
Display 1: Asset Performance Year-to-Date
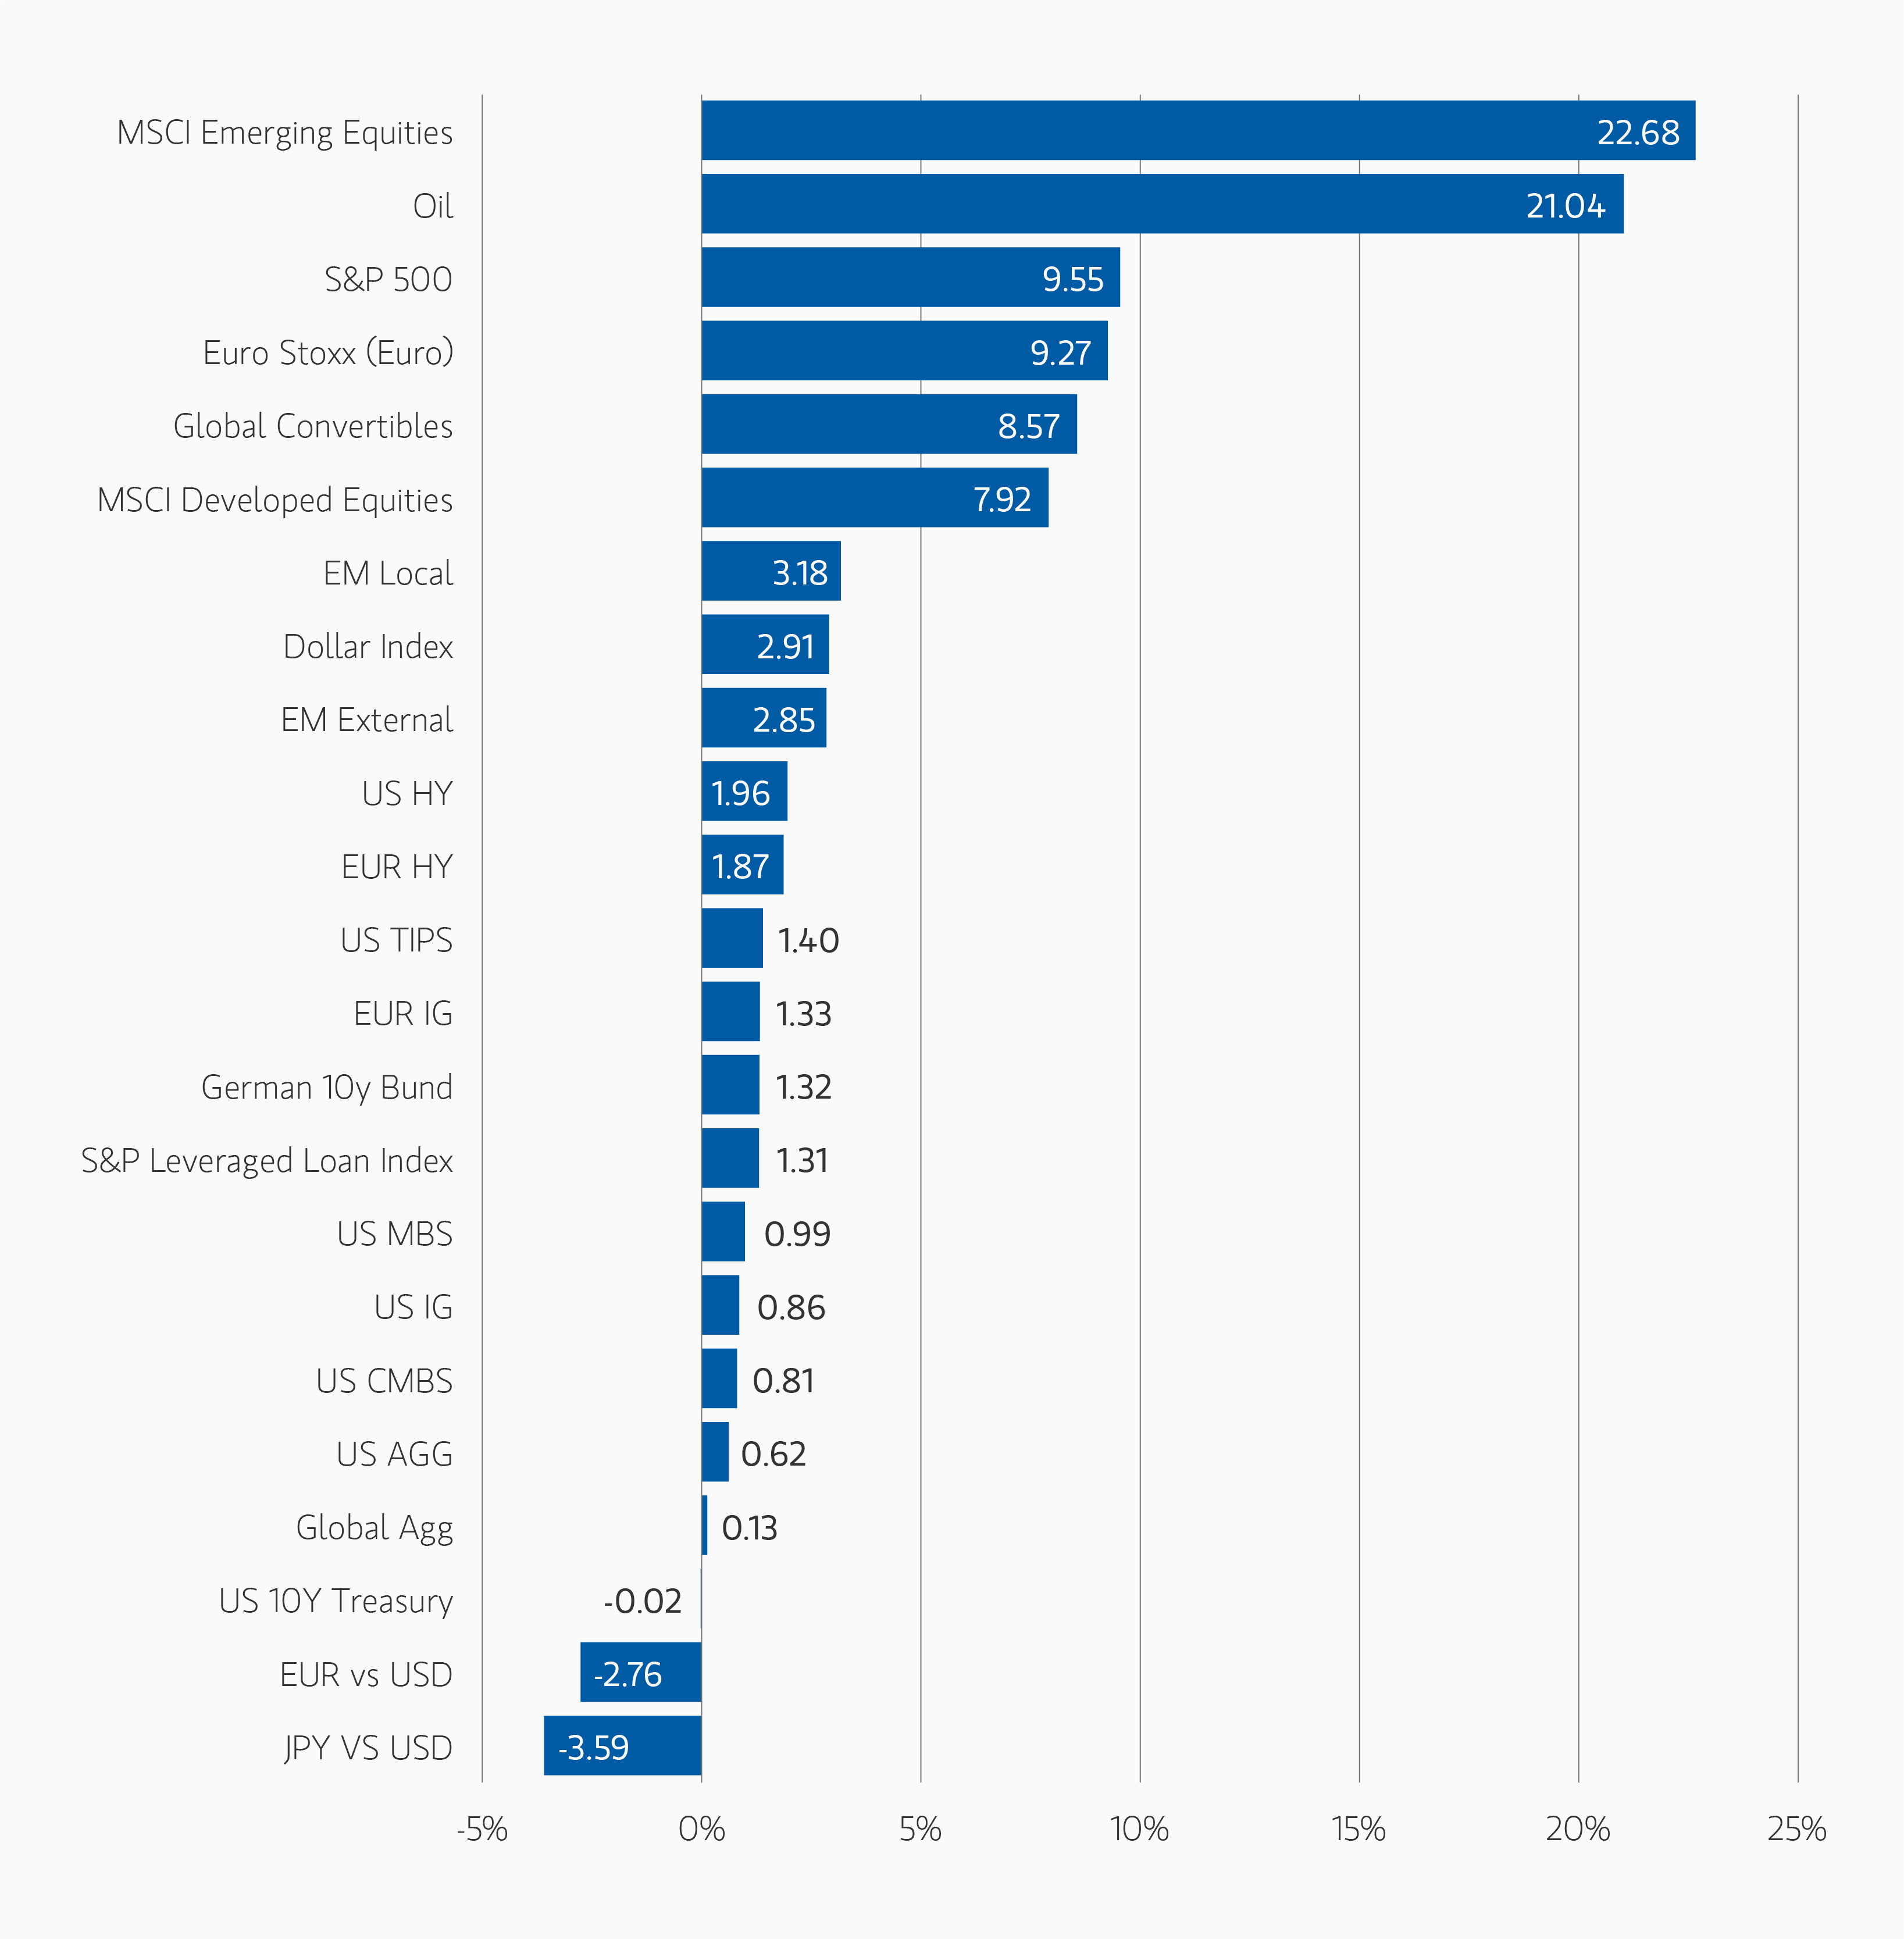
Note: USD-based performance. Source: Bloomberg. Data as of August 31, 2026. The indexes are provided for illustrative purposes only and are not meant to depict the performance of a specific investment. Past performance is no guarantee of future results.
Display 1: Asset Performance Year-to-Date
Display 2: Currency Monthly Changes versus USD
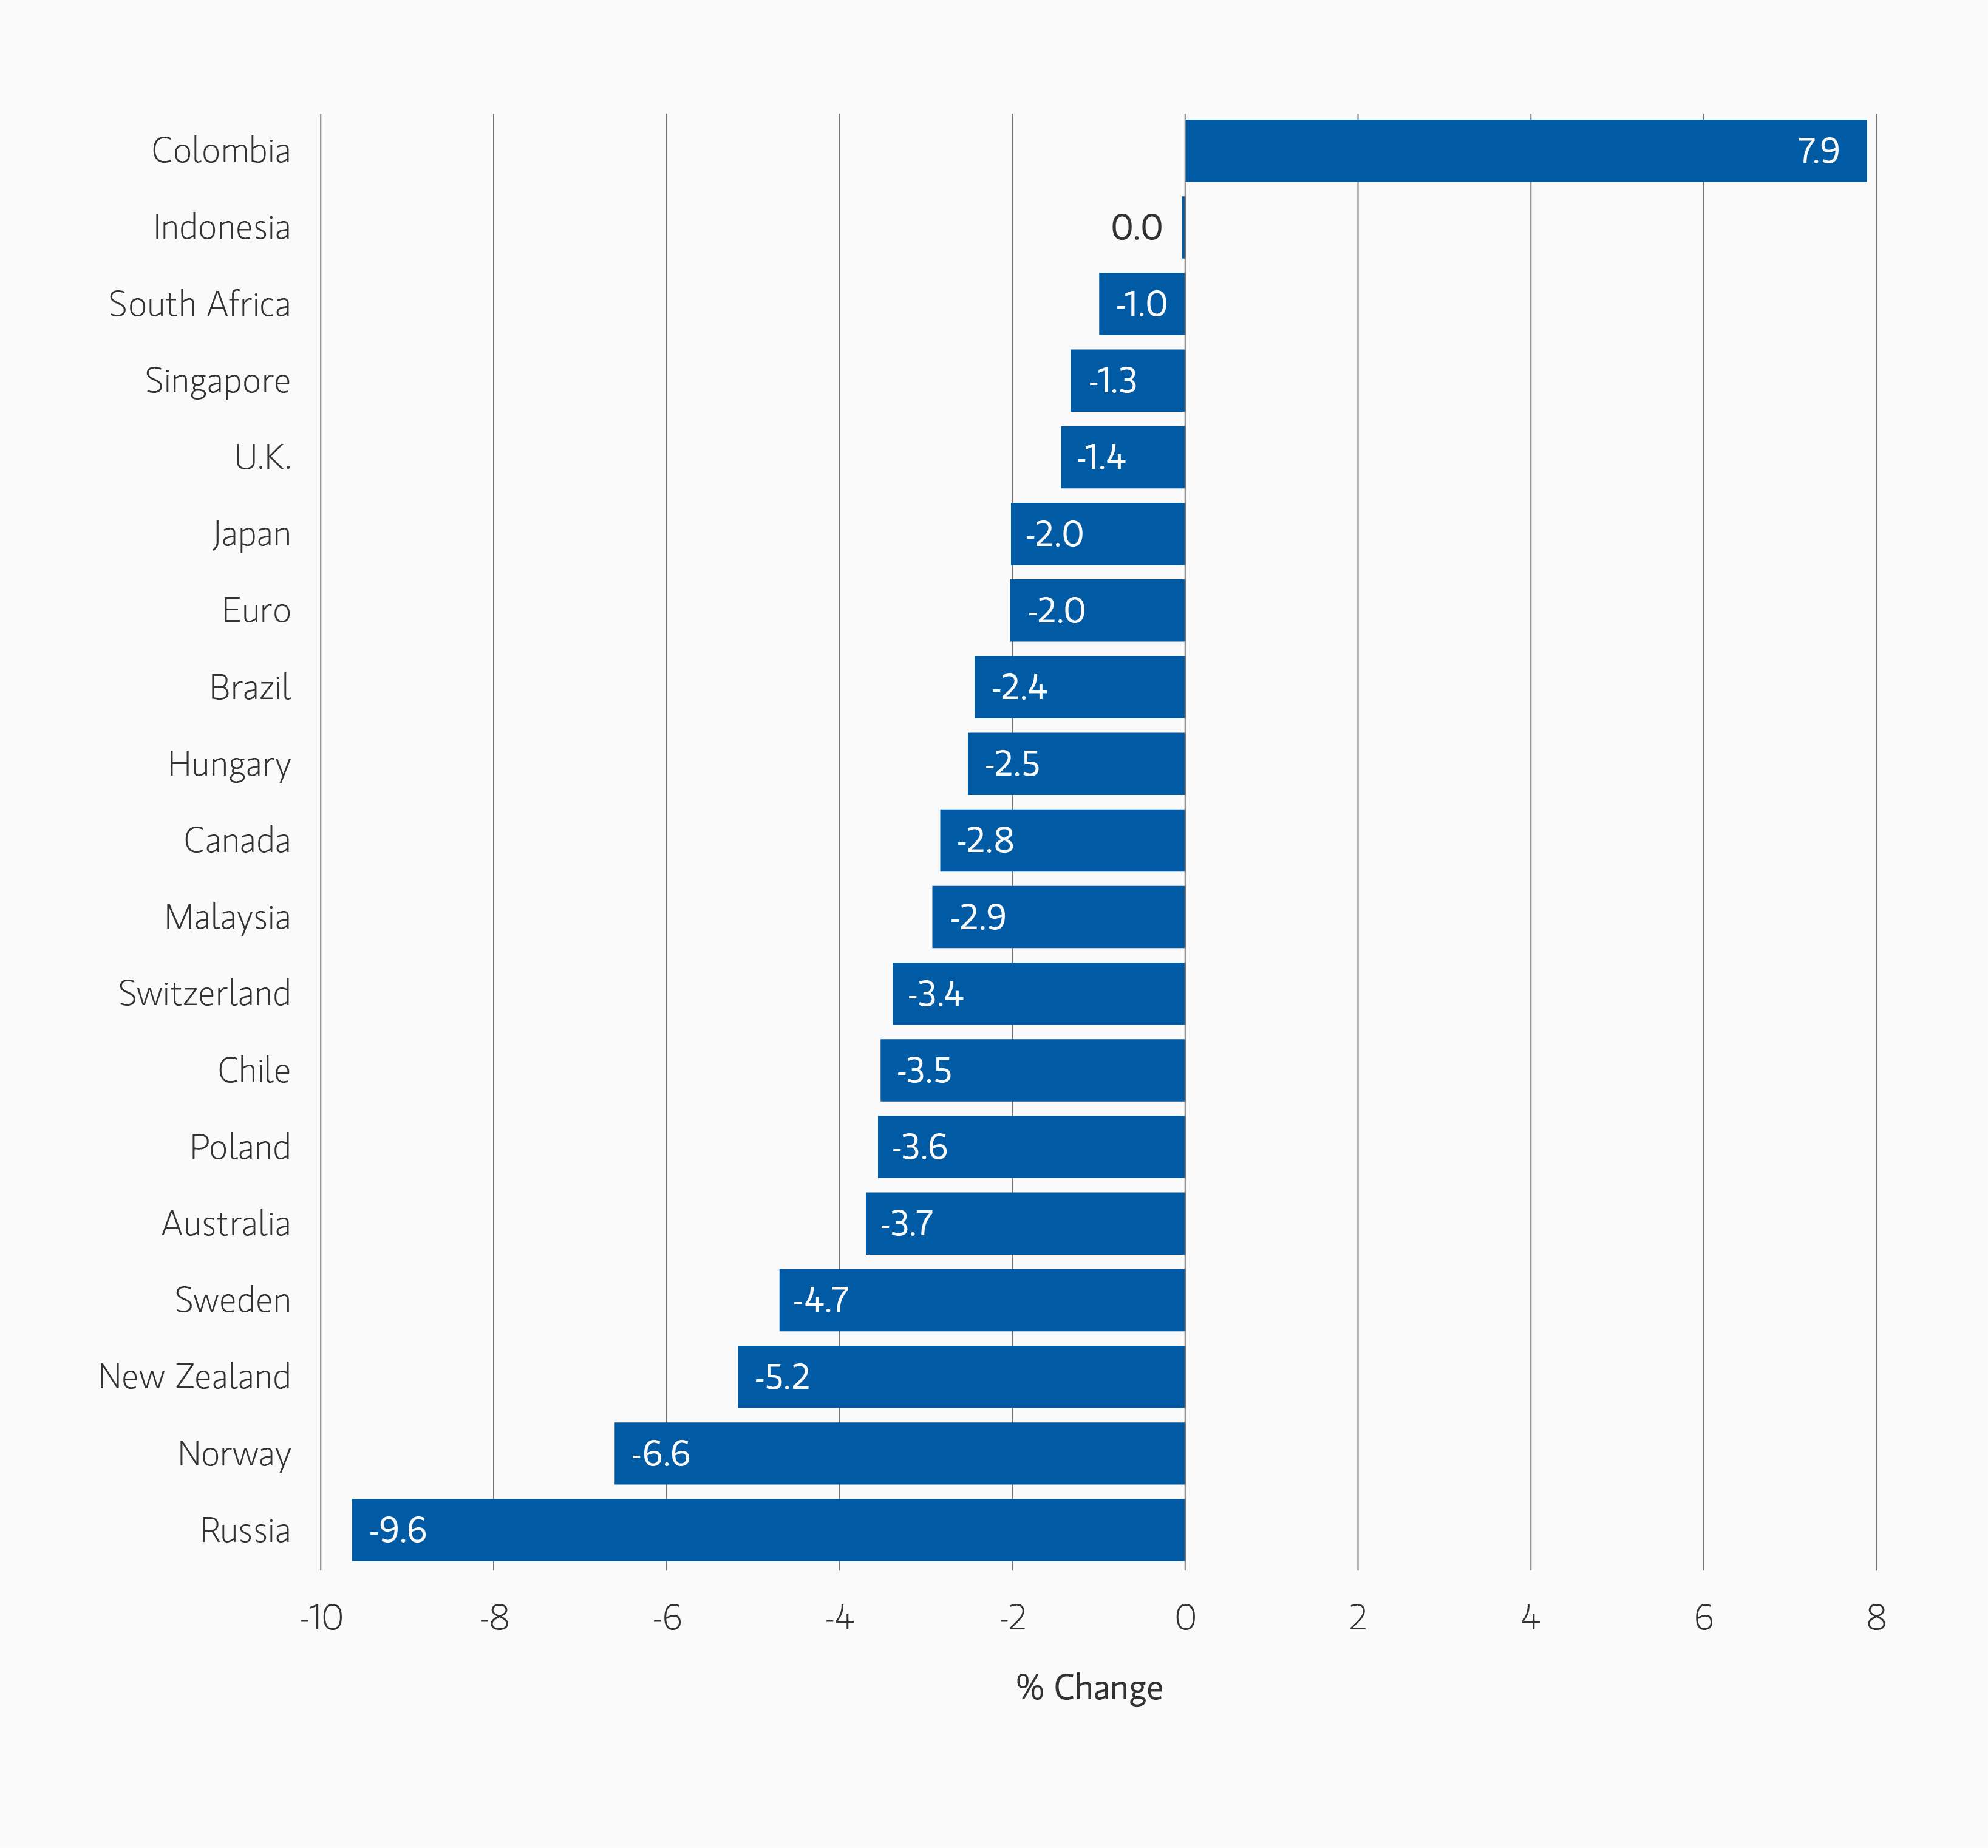
Note: Positive change means appreciation of the currency against the USD. Source: Bloomberg. Data as of August 31, 2026.
Display 2: Currency Monthly Changes versus USD
Display 3: Major Monthly Changes in 10-Year Yields and Spreads
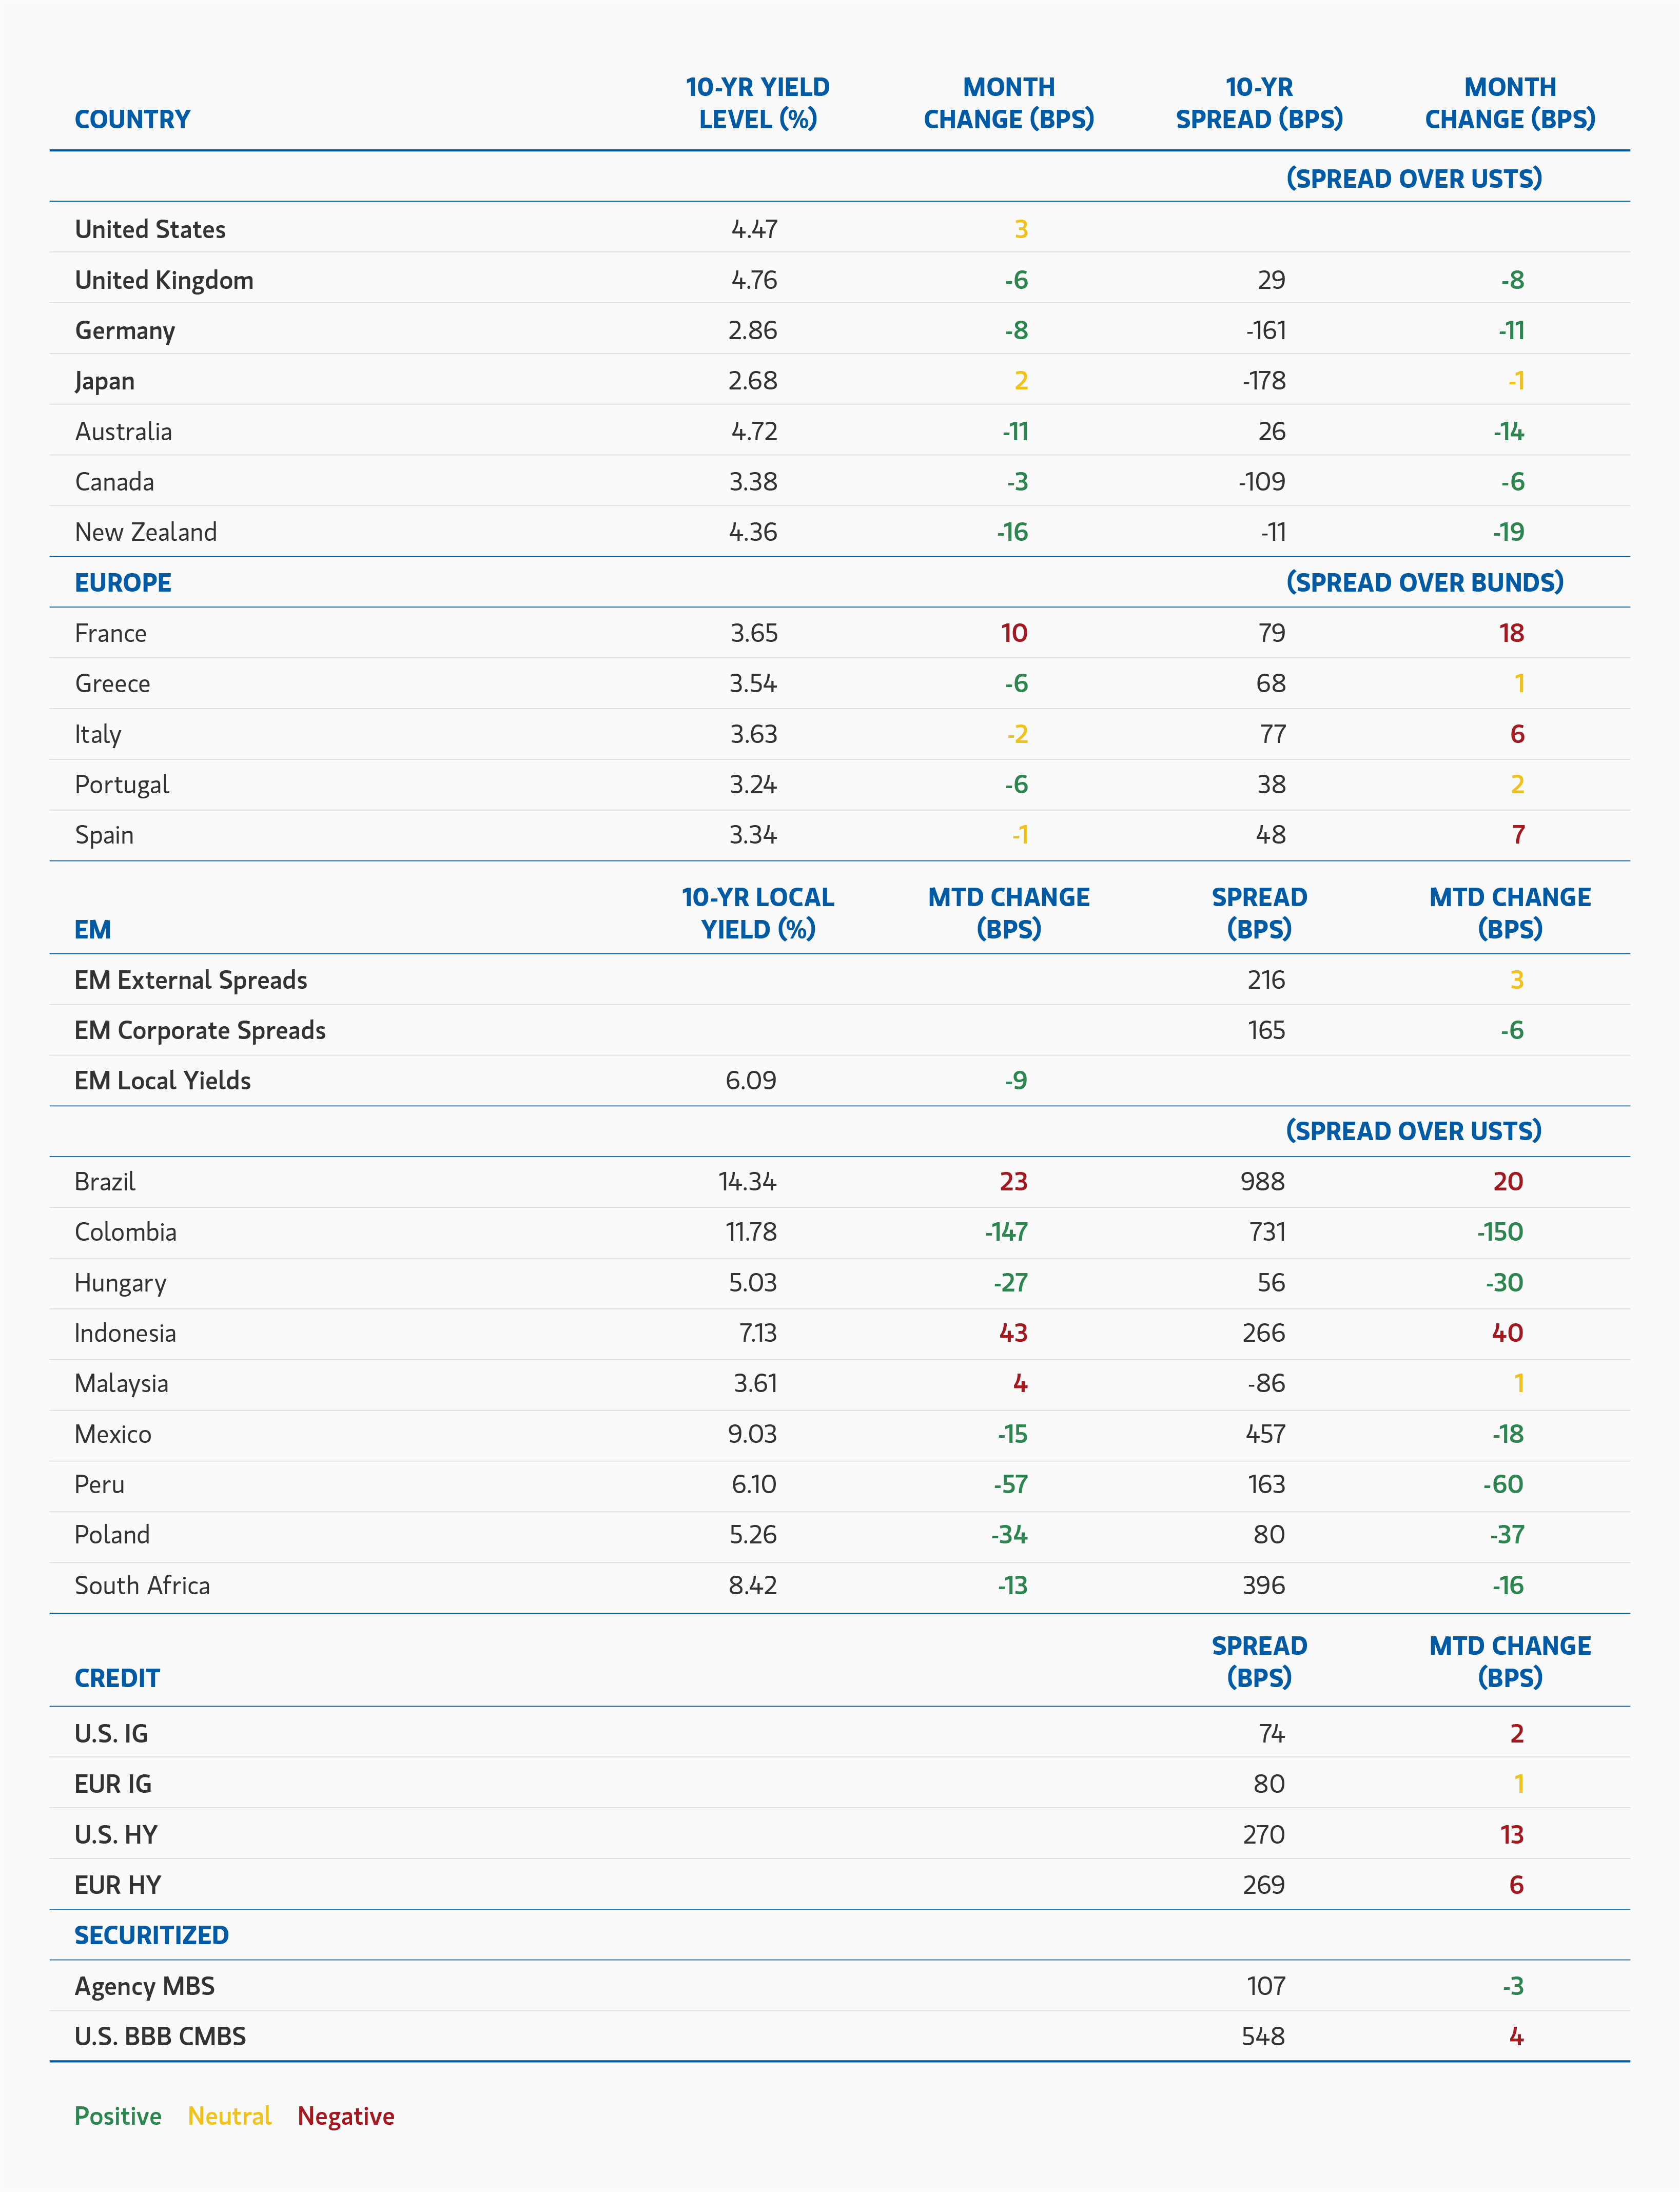
Source: Bloomberg, JPMorgan. Data as of August 31, 2026.
Display 3: Major Monthly Changes in 10-Year Yields and Spreads
Broad Markets Fixed Income Global Asset Allocation and Outlook
Developed Market Rate/Foreign Currency
(Long duration, neutral curve positioning, selective high-carry FX)
Our views are grounded in a macro environment where country differentiation is becoming increasingly important. In the U.S., resilient labor-market data, firm consumption, and persistent inflation pressures have led investors to reprice monetary-policy expectations toward a more restrictive path than was anticipated at the beginning of the year. Elsewhere in developed markets, much of this adjustment occurred earlier, though inflation, energy prices, fiscal dynamics, and differing growth trajectories continue to shape central-bank expectations.
Against this backdrop, we maintain a long-duration stance across developed markets, expressed selectively in regions where growth appears more vulnerable to tighter financial conditions and valuations are compelling. Exposure remains focused on short-maturity rates in Canada and New Zealand, alongside selective euro-area duration, including France. This positioning reflects the greater scope for economic weakness outside the U.S. and the potential for regional policy paths to diverge.
Inflation remains a central macro risk. Although market-implied inflation expectations have fluctuated, underlying price pressures and uncertainty around the Federal Reserve’s reaction function continue to support exposure through U.S. breakevens across intermediate and longer maturities. We continue to see value in hedging portfolios against the risk that inflation remains above target for longer than markets currently anticipate.
We remain broadly neutral on directional curve exposure, while retaining selective relative-value positions where differences in policy, growth, and valuation create more attractive opportunities. These include cross-market positions within Europe and targeted curve exposure in Australia, rather than a broad global steepening or flattening view.
In foreign exchange, we continue to favor selective high-carry emerging-market currencies where fundamentals and valuations remain supportive. Our positive view is focused on the Mexican peso, funded against lower-yielding European currencies including the euro, Swiss franc, and Swedish krona. More broadly, we expect currency markets to remain sensitive to relative growth, inflation, and central-bank dynamics, with country differentiation continuing to create opportunities across both developed and emerging markets.
Emerging Market Debt
(Overweight)
Emerging market sovereign and corporate debt remains an attractive opportunity, supported by elevated real yields, resilient income generation, and improving fundamentals in select countries. August saw a broad recovery in hard-currency spreads despite continued uncertainty around developed-market policy, reinforcing the asset class's carry appeal while also highlighting the importance of country and regional differentiation.
Carry and income remain central drivers of expected returns, though country selection is increasingly important given elevated dispersion. Recent performance continued to demonstrate that local political developments, policy decisions, and external balances can be more important than the broader global rates backdrop. We continue to favor markets where credible monetary frameworks, improving fundamentals, and supportive capital-flow dynamics provide a stronger foundation for returns.
Valuations remain attractive across select local- and hard-currency markets, while many EM currencies continue to offer compelling carry relative to developed markets. Higher global yields, persistent inflation, and geopolitical uncertainty remain important risks, but the broad tightening in sovereign and corporate spreads during August suggests that demand for income remains resilient. In an environment where global growth remains positive and default risks remain contained, we believe the asset class continues to offer attractive risk-adjusted return potential.
Corporate Credit
(Underweight Investment Grade (IG), small overweight high yield (HY))
We remain underweight investment grade corporates due to tight valuations and limited scope for broad-based spread compression. Investment grade spreads were notably stable in August despite meaningful repricing of the policy outlook, reinforcing the view that the market is increasingly dependent on technical demand and attractive all-in yields rather than further spread tightening. Carry therefore remains the principal source of expected return, while tight starting spreads leave limited scope for risk mitigation against renewed volatility.
Fundamentals remain solid, supported by healthy balance sheets, low downgrade risk, and generally resilient earnings. However, later-cycle pressures continue to build through elevated M&A activity, AI- and infrastructure-related capital expenditure, and higher shareholder distributions. AI-related financing remains an important driver of issuance, particularly among large technology and hyperscale issuers, reinforcing the need for greater selectivity as balance-sheet demands increase.
Regionally, we continue to prefer Europe over the U.S., supported by stronger technicals and resilient spread performance. Within the U.S., we favor financials and utilities over industrials and lower-quality non-financial issuers, where capex, M&A activity, and shareholder distributions may create greater balance-sheet pressure. We remain particularly selective in sectors where technological disruption or speculative financing activity could weaken credit quality.
We maintain a modest overweight to select high-yield issuers in both the U.S. and Europe. August's rally was concentrated in BB and single-B credits, while CCC-rated debt weakened, reinforcing our preference for higher-quality high yield rather than broad beta exposure. The divergence suggests that demand remains focused on carry and income in stronger credits rather than reflecting a generalized improvement in lower-quality fundamentals. We therefore continue to favor issuers with resilient cash flows, manageable refinancing needs, and less exposure to speculative or highly cyclical business models.
We continue to believe a meaningful demand-destruction scenario is not the base case. Low but positive economic growth, supported by fiscal spending, energy-related investment, and continued AI and infrastructure capex, remains consistent with a broadly benign default environment. However, with much of the good news already reflected in valuations, selectivity remains increasingly important.
Elevated dispersion across sectors, issuers, and ratings continues to create opportunities for active positioning. We favor businesses with resilient cash flows, strong pricing power, lower refinancing risk, and less exposure to cyclical demand pressure. While high-yield spreads leave limited margin for error, the yield per unit of spread-duration risk remains compelling relative to investment grade credit.
Leveraged Loans
(Neutral)
We maintain a neutral stance on leveraged loans as dispersion and prior spread widening have improved valuations across parts of the market. The asset class remains characterized by meaningful issuer-level differentiation, while CLO demand continues to provide an important source of technical support. Investor preference remains focused on higher-quality issuers and more resilient sectors, where current valuations provide better compensation for refinancing and macroeconomic risks.
Software and technology-linked issuers remain an area of caution given ongoing uncertainty around AI-related disruption. However, the broad-based selloff across parts of the sector has also created selective opportunities where market pricing appears disconnected from underlying fundamentals. We continue to favor higher-quality, mission-critical businesses with durable cash flows, proprietary data advantages, and high switching costs.
More broadly, elevated financing costs and persistent inflation uncertainty continue to pressure highly leveraged borrowers, even as overall corporate fundamentals remain relatively stable. The possibility of renewed central-bank tightening reinforces our preference for issuers with strong interest coverage, manageable maturity profiles, and durable cash-flow generation.
CLO issuance and demand for floating-rate exposure remain supportive, helping offset more mixed retail flows. While selectivity remains paramount, current valuations continue to provide improved, though still selective, compensation for refinancing and macroeconomic risks in higher-quality segments of the market.
Securitized Products
(Overweight)
Agency mortgage-backed securities and non-agency residential mortgage-backed securities (RMBS) remain a high-conviction overweight. Agency MBS benefited from the decline in rate volatility during August, with spreads tightening as the rates market became more orderly and mortgage rates eased modestly. We continue to view current-coupon agency MBS as attractive relative to other high-quality fixed income sectors, supported by compelling all-in yields, reduced prepayment risk, and improved relative value following the widening seen earlier in the summer.
Technical conditions remain broadly supportive, although the sector remains sensitive to changes in rate volatility. Attractive all-in yields continue to support demand from money managers, banks, and government-sponsored enterprises, while Federal Reserve balance-sheet runoff remains a source of supply. A renewed rise in volatility or a sharp move in the long end would remain the principal near-term risks, but August demonstrated the benefit of a more stable rates environment for agency MBS.
Non-agency RMBS continues to offer one of the more attractive opportunity sets within structured credit. Stable home prices, low loan-to-value ratios, improving collateral performance, and limited refinancing risk continue to support fundamentals. Strong issuance growth has been met with robust investor demand, particularly in residential credit sectors where recent vintages continue to demonstrate favorable performance characteristics.
Securitized credit remained broadly resilient during August. CMBS and ABS spreads moved only modestly, reinforcing the view that sector performance continues to be driven primarily by technical conditions and the rates-volatility backdrop rather than any meaningful deterioration in underlying collateral fundamentals.
Commercial mortgage-backed securities remain an attractive area of structured credit, though selectivity remains critical. Fundamentals are resilient in higher-quality segments, and strong technical demand continues to support the sector despite elevated financing costs. We continue to favor hospitality, logistics, storage, and high-quality multifamily assets, where operating performance and collateral quality remain comparatively strong.
Issuance across securitized markets, including CMBS, remains robust, but transactions have generally been well absorbed, reinforcing the strength of investor demand. Dispersion across property types, locations, and capital structures remains elevated, and we continue to focus on higher-quality transactions where collateral performance, borrower sponsorship, and cash-flow visibility provide stronger downside protection and risk mitigation.
Asset-backed securities remain supported by strong demand, attractive carry, and the sector's generally shorter-duration profile. Issuance has remained elevated, but demand for high-quality securitized collateral continues to help keep spreads contained. We continue to view the sector as a useful source of diversification and income in an environment where carry remains an important driver of returns.
We also continue to see opportunities in select non-consumer ABS where fundamentals remain stable and valuations remain attractive. We remain more cautious in areas where projected supply, technology disruption, or uncertain long-term economics are not adequately reflected in spreads.
Lastly, we remain constructive on Danish covered bonds, where defensive characteristics, strong legal frameworks, and attractive U.S. dollar-hedged yields continue to support relative value.
Featured Insights


